Streamlining Cash Flow by Factoring

 In today’s market, maintaining steady cash flow is more critical than ever for business growth.
Streamlining Your Clients' Cash Flow with Factoring

At Versant Funding, we specialize in non-recourse accounts receivable factoring designed to unlock capital quickly—without traditional lending roadblocks.

When evaluating a company for financing, Versant focuses exclusively on the quality of their accounts receivable.

That enables us to fund businesses which do not meet bank financing standards provided they have a strong customer base.

Accounts Receivable Factoring
$100,000 to $30 Million
Quick AR Advances
No Long-Term Commitment
Non-recourse
Funding in about a week

We are a great match for businesses with traits such as:
Less than 2 years old
Negative Net Worth
Losses
Customer Concentrations
Weak Credit Character Issues

Contact me today to learn if your client is a factoring fit.
Chris Lehnes
203-664-1535
chris@chrislehnes.com
Connect on LinkedIn

 In today’s market, maintaining steady cash flow is more critical than ever for business growth.

 In today's market, maintaining steady cash flow is more critical than ever for business growth.

At Versant Funding, we specialize in non-recourse accounts receivable factoring designed to unlock capital quickly—without traditional lending roadblocks.

When evaluating a company for financing, Versant focuses exclusively on the quality of their accounts receivable.

That enables us to fund businesses which do not meet bank financing standards provided they have a strong customer base.

Accounts Receivable Factoring
$100,000 to $30 Million
Quick AR Advances
No Long-Term Commitment
Non-recourse
Funding in about a week

We are a great match for businesses with traits such as:
Less than 2 years old
Negative Net Worth
Losses
Customer Concentrations
Weak Credit Character Issues

Contact me today to learn if your client is a factoring fit.

90 Second Book Summary: “The Psychology of AI Adoption at Work” by Dr. Gleb Tsipursky.

Dr. Gleb Tsipursky postulates that AI roll-outs usually fail because leaders completely ignore the human responses to it.

90 Second Book Summary: "The Psychology of AI Adoption at Work" by Dr. Gleb Tsipursky.

The real barrier is automation anxiety; employees literally fearing they are training their robotic replacements, and the status quo bias.

Employees deeply distrust “black box” software handed down by management.

The author recommends taking steps to involve employees in implementation to encourage their buy-in, focusing on pulling the most stubborn complainers into the process.

To truly win with generative AR, Dr. Tsipursky states it is essential to consider the hearts and minds of the workforce.

“This is the brief on the psychology of AI adoption at work. So in his 2026 book, The Psychology of AI Adoption at Work, Dr. Gleb Tsipursky points out that corporate AI roll-outs usually fail because leaders completely ignore the messy, emotional human response to it.

Now, you might be wondering, if this generative AI tech is so incredibly powerful, why are so many roll-outs totally flat-lining?

Well, first, it’s all about the psychological roadblock. The real barrier is automation anxiety—people literally fearing they’re training their robotic replacements—and the status quo bias. Employees deeply mistrust black-box software handed down from management. Dropping a shiny, mysterious AI tool on a stressed-out team without emotional support is like handing someone the keys to a race car without teaching them how to drive. They’re just going to be terrified.

Second, we need an empowerment solution. Instead of buying expensive, opaque vendor software, let your front line workers use simple no-code, drag-and-drop tools to build their own custom AI assistants for their specific daily headaches. You know, it’s the classic IKEA effect: when we build the furniture ourselves, we love it way more. People just naturally support what they create.

Finally, how do you actually scale this across the whole company without total chaos? You leverage the extremes. Identify your enthusiastic shadow AI users secretly breaking the rules, and officially promote them to peer mentors. At the same time, put your biggest doubters—those pragmatic resistors—on your AI advisory boards to stress-test everything. Wait, literally put your most stubborn complainers in charge of testing the AI? Absolutely, because they will find the flaws faster than anyone else.

To truly win with generative AI, organizations absolutely have to manage the hearts and minds of their workforce, not just the code and data.”

Contact Factoring Specialist, Chris Lehnes

Read a sample or purchase here

Here is an outline summarizing the core concepts and frameworks from the document:

  • Executive Summary and Core Premise:
    • Human-centric integration: Generative AI (Gen AI) transforms organizations when implemented through empathetic leadership, cultural readiness, and continuous learning, rather than as a top-down IT installation.
    • Empowerment approach: Enabling internal teams through low-code/no-code platforms to build, adapt, and own custom AI tools reduces resistance, avoids black-box vendor lock-in, and compounds organizational learning.
  • Evolution from Traditional ML to Generative AI:
    • Predictive vs. generative capabilities: Traditional machine learning optimizes existing processes using clean historical data, whereas Gen AI generates novel content, automates knowledge work, and democratizes advanced capabilities for midsize firms.
    • Empirical business impact: Studies demonstrate that thoughtful Gen AI implementation increases developer coding speed by 30–50%, accelerates writing tasks by 37%, elevates lower-skilled worker output, and delivers measurable revenue expansion.
  • Psychological and Structural Barriers to Adoption:
    • Attitudinal and emotional blockers: Trust in AI is declining globally due to black-box opacity, high-profile AI hallucinations, data privacy fears, and automation anxiety driven by loss aversion and identity threats.
    • Technical and organizational roadblocks: Technical integration is hindered by legacy enterprise systems, data quality issues, and talent shortages; structural failure stems from scattered pilot projects, lack of governance, and inadequate change management.
  • Risk Management and Ethical Stewardship:
    • Multidimensional threat landscape: Organizations face security vulnerabilities like prompt injection and jailbreaking, severe PR risks from AI misstatements, inherent dataset bias, and principal-agent alignment issues like “reward hacking”.
    • Governance infrastructure: Mitigation requires interdisciplinary AI governance councils, specialized roles like AI Ethicists and AI Risk Managers, clear data tiering, and proactive crisis-response plans.
  • Psychographic Profiles of Managers and Employees:
    • Middle-manager attitudes: Middle managers manage frontline anxieties while pursuing executive goals, falling along a spectrum: AI Skeptics, Wait-and-See Traditionalists, Cautious Implementers, Enthusiastic Experimenters, and AI Catalysts.
    • Employee attitudes: Nonmanagerial staff exhibit eight distinct archetypes ranging from resistant to enthusiastic: AI Alarmists, Pragmatic Resisters, Skeptical Observers, Apathetic Bystanders, Reluctant Adopters, Cautious Optimists, Efficiency Seekers, and AI Evangelists.
  • Strategies for Engagement, Upskilling, and Innovation:
    • Targeted engagement and Choice Architecture: Leaders must use surveys and focus groups to gauge sentiment, construct behavioral “nudges” and optimal defaults to reduce friction, and harness hidden “shadow users” into mentored champion networks.
    • Continuous learning and co-creation: AI upskilling should be role-specific, microlearning-driven, and embedded in daily workflows, creating a safe, fail-forward culture that leverages human-AI co-creation to drive product, operational, and business model innovation.
  • Measurement and Long-Term Strategic Planning:
    • Multidimensional KPI dashboards: Organizations must track adoption depth, efficiency gains, business impact, employee satisfaction, capability transfer, and compliance metrics to prove tangible ROI.
    • Three-year transformation roadmap: Long-term strategy progresses from Year 1 (foundational enablement, narrow use-case builds, and champion activation) to Year 2 (workflow integration, capability badges, and scaling reskilling) and Year 3 (institutionalized assistant catalogs, vendor diversification, and preparing for agentic AI and robotics).

Funding for Bank Declines

There are many reasons a business may be declined for bank financing. At Versant Funding, most of those reasons are irrelevant. Most businesses with good quality accounts receivable are candidates for our factoring program.

There are many reasons a business may be declined for bank financing. At Versant Funding, most of those reasons are irrelevant. Most businesses with good quality accounts receivable are candidates for our factoring program.

When evaluating a company for financing, Versant focuses exclusively on the quality of their accounts receivable. That enables us to fund businesses which do not meet bank financing standards.

Program Overview

  • $100,000 to $30 Million
  • Quick AR Advances
  • No Long-Term Commitment
  • Non-recourse
  • Flexible Terms

We are a great match for businesses with traits such as:

  • Less than 2 years old
  • Negative Net Worth
  • Losses
  • Customer Concentrations
  • Weak Credit
  • Foreign Ownership
  • Character Issues

Our AR-focused underwriting allows us to move quickly and fund qualified businesses including Manufacturers, Distributors and a wide variety of Service Businesses (including SaaS) in as few as 3-5 days.

Contact me to learn how your client can use factoring as a bridge to profitability.

When evaluating a company for financing, Versant focuses exclusively on the quality of their accounts receivable. That enables us to fund businesses which do not meet bank financing standards.

Program Overview

  • $100,000 to $30 Million
  • Quick AR Advances
  • No Long-Term Commitment
  • Non-recourse
  • Flexible Terms

We are a great match for businesses with traits such as:

  • Less than 2 years old
  • Negative Net Worth
  • Losses
  • Customer Concentrations
  • Weak Credit
  • Foreign Ownership
  • Character Issues

Our AR-focused underwriting allows us to move quickly and fund qualified businesses including Manufacturers, Distributors and a wide variety of Service Businesses (including SaaS) in as few as 3-5 days.

Our AR-focused underwriting allows us to move quickly and fund qualified businesses including Manufacturers, Distributors and a wide variety of Service Businesses (including SaaS) in as few as 3-5 days.

Contact me to learn how your client can use factoring as a bridge to profitability.

There are many reasons a business may be declined for bank financing. At Versant Funding, most of those reasons are irrelevant. Most businesses with good quality accounts receivable are candidates for our factoring program.

Revitalizing a Manufacturer Grappling with Liquidity

Just spoke to the CEO of a Midwest-based, old-school manufacturing company.

Founded in the 1910s.

Steel is a vital input in their production.

Their customer base is full of other old-school manufacturers that use the components they produce.

The company was essentially dormant a year ago, but the new CEO is turning it around.

I had the opportunity to tell him about factoring and how we could provide the company the liquidity needed to expand.

He LOVES the concept!

We issued our proposal soon after.

I’d like nothing more than to fill our portfolio with companies like this.

Contact me to learn if your manufacturer client is a factoring fit.

Revitalizing an Old-school Manufacturer. Spoke to the CEO of a Midwest manufacturing company. I'd love to fill our portfolio with companies like this

Breathing New Life into Legacy Manufacturing: How Factoring Fuels a Turnaround

I recently had a conversation with the new CEO of a Midwest-based manufacturing company. This isn’t a tech startup or a flashy new enterprise—it’s an old-school, foundational American business. Founded in the 1910s, this company has weathered over a century of economic cycles, market shifts, and industrial evolution.

Their core operation relies heavily on steel to produce components for a customer base made up entirely of other legacy manufacturers. Yet, despite its rich history and solid market niche, the company was essentially dormant just a year ago. Now, under the guidance of a new CEO, the engines are firing back up, and a major turnaround is underway.

But as any turnaround specialist will tell you, vision and market demand are only half the battle. The other half is liquidity.

The Capital Challenge of a Turnaround

Manufacturing is exceptionally capital-intensive. Before a single finished component can be shipped to a customer, raw materials—in this case, steel—must be purchased, and overhead must be covered.

For a company that was dormant just twelve months prior, traditional financing is rarely an option. Banks and conventional lenders look backward; they require years of steady, positive cash flow and pristine balance sheets to underwrite a loan. They see a recent period of dormancy as a red flag. As a result, even the most promising turnaround can stall out before it begins simply because the capital isn’t there to fulfill incoming orders.

Why Factoring is the Perfect Fit

This is where the conversation with the CEO became interesting. I had the opportunity to introduce him to the mechanics of accounts receivable factoring and explain exactly how it bypasses the hurdles of traditional lending.

Because this manufacturer sells to a strong B2B customer base of established industrial companies, they are sitting on a highly valuable, untapped asset: their accounts receivable.

Factoring doesn’t rely on the manufacturer’s historical financial performance or recent dormancy. Instead, it leverages the creditworthiness of their customers. By selling their outstanding invoices, the manufacturer can unlock immediate working capital.

During our discussion, the CEO immediately saw the strategic advantage. Factoring provides the exact mechanism they need to:

  • Purchase Raw Materials: Secure the steel required for production without waiting 30 to 60 days for previous customer invoices to clear.
  • Fulfill Larger Orders: Take on new business with confidence, knowing the capital is available to execute.
  • Scale Without Debt: Generate liquidity organically through their own sales rather than taking on restrictive bank loans.

He loved the concept. It was the missing puzzle piece for his turnaround strategy, and we were able to issue a tailored proposal shortly after our call.

Fueling American Industry

There is something deeply rewarding about helping a century-old business get back on its feet. Providing the liquidity needed to turn the lights back on, get machines running, and put people back to work is exactly why this industry is so vital.

We are actively looking to fill our portfolio with resilient, high-potential companies just like this one—businesses that have the drive, the customers, and the product, but just need the working capital to make it happen.

If you are working with a manufacturing client—whether they are navigating a turnaround, experiencing rapid growth, or simply struggling with cash flow tied up in slow-paying B2B invoices—let’s connect. Reach out to discuss how a strategic factoring facility can provide the liquidity they need to expand.
An Innovative Funding Option for Unprofitable Businesses

Unprofitable Businesses often find securing financing a challenge. Many lenders are focused on the financial performance of their borrowers and will quickly decline businesses without sufficient historic and projected debt service coverage.

Businesses which are reporting losses often find securing financing a challenge. Many lenders are focused on the financial performance of their borrowers and will quickly decline businesses without sufficient historic and projected debt service coverage.

Versant’s factoring program can be a readily-accessible source of financing for businesses which are not generating profits, but have accounts receivable due from creditworthy customers.

When evaluating a company for financing, Versant focuses exclusively on the quality of their accounts receivable. That enables us to fund businesses which are do not meet traditional lending standards.

Program Overview

  • $100,000 to $30 Million
  • Quick AR Advances
  • No Long-Term Commitment
  • Non-recourse
  • Flexible Terms

We are a great match for businesses with traits such as:

  • Less than 2 years old
  • Negative Net Worth
  • Losses
  • Customer Concentrations
  • Weak Credit
  • Foreign Ownership
  • Character Issues

Our AR-centric approach enables us to move quickly and fund qualified businesses including Manufacturers, Distributors and a wide variety of Service Businesses (including SaaS) in as few as 3-5 days.

Contact me today to learn how your client can use factoring as a bridge to profitability.

Businesses which are reporting losses often find securing financing a challenge. Many lenders are focused on the financial performance of their borrowers and will quickly decline businesses without sufficient historic and projected debt service coverage.

Unprofitable Businesses often find securing financing a challenge. Many lenders are focused on the financial performance of their borrowers and will quickly decline businesses without sufficient historic and projected debt service coverage.

Versant’s factoring program can be a readily-accessible source of financing for businesses which are not generating profits, but have accounts receivable due from creditworthy customers.

When evaluating a company for financing, Versant focuses exclusively on the quality of their accounts receivable. That enables us to fund businesses which are do not meet traditional lending standards.

Program Overview

  • $100,000 to $30 Million
  • Quick AR Advances
  • No Long-Term Commitment
  • Non-recourse
  • Flexible Terms

We are a great match for businesses with traits such as:

  • Less than 2 years old
  • Negative Net Worth
  • Losses
  • Customer Concentrations
  • Weak Credit
  • Foreign Ownership
  • Character Issues

Our AR-centric approach enables us to move quickly and fund qualified businesses including Manufacturers, Distributors and a wide variety of Service Businesses (including SaaS) in as few as 3-5 days.

Contact me today to learn how your client can use factoring as a bridge to profitability.

A Funding Option for Customer Concentrations

Businesses with customer concentrations often find securing financing a challenge. Many lenders will decline them outright or place funding limits to reduce their exposure to what is perceived as a high-risk transaction.

Businesses with customer concentrations often find securing financing a challenge. Many lenders will decline them outright or place funding limits to reduce their exposure to what is perceived as a high-risk transaction.

Versant’s factoring program can be an ideal source of financing for businesses with customer concentrations, including those with only a single customer (100% concentration.)

When evaluating a company for financing, Versant focuses exclusively on the quality of their accounts receivable. That enables us to fund businesses with high customer concentrations provided those customers possess a strong credit profile.

Program Overview

  • $100,000 to $30 Million
  • Quick AR Advances
  • No Long-Term Commitment
  • Non-recourse
  • Flexible Terms

We are a great match for businesses with traits such as:

  • Less than 2 years old
  • Negative Net Worth
  • Losses
  • Customer Concentrations
  • Weak Credit
  • Foreign Ownership
  • Character Issues

Our AR-centric approach enables us to move quickly and fund qualified businesses including Manufacturers, Distributors and a wide variety of Service Businesses (including SaaS) in as few as 3-5 days.

Contact me today to learn if your client is a factoring fit..

Businesses with customer concentrations often find securing financing a challenge. Many lenders will decline them outright or place funding limits to reduce their exposure to what is perceived as a high-risk transaction.

A Funding Option for Foreign Ownership

Recent changes to SBA loan regulations have rendered businesses which are not 100% owned by US citizens ineligible for SBA financing. This update has left many businesses with partial ownership by foreign nationals scrambling for an alternative source of financing

Recent changes to SBA loan regulations have rendered businesses which are not 100% owned by US citizens ineligible for SBA financing. This update has left many businesses with partial ownership by foreign nationals scrambling for an alternative source of financing

When evaluating a company for financing, Versant focuses exclusively on the quality of accounts receivable. The personal credit, management experience and nationality of the owners are not part of our underwriting.

Versant’s factoring program can be a convenient source of financing for businesses which are no longer candidates for SBA financing and need an immediate source of working capital.

Program Overview

  • $100,000 to $30 Million
  • Quick AR Advances
  • No Long-Term Commitment
  • Non-recourse
  • Flexible Terms

We are a great match for businesses with traits such as:

  • Less than 2 years old
  • Negative Net Worth
  • Losses
  • Customer Concentrations
  • Weak Credit
  • Foreign Ownership
  • Character Issues

Our AR-centric approach enables us to move quickly and fund qualified businesses including Manufacturers, Distributors and a wide variety of Service Businesses (including SaaS) in as few as 3-5 days.

Contact me today to learn if your client is a factoring fit.

Chris Lehnes

203-664-1535

clehnes@VersantFunding.com

Learn more about factoring

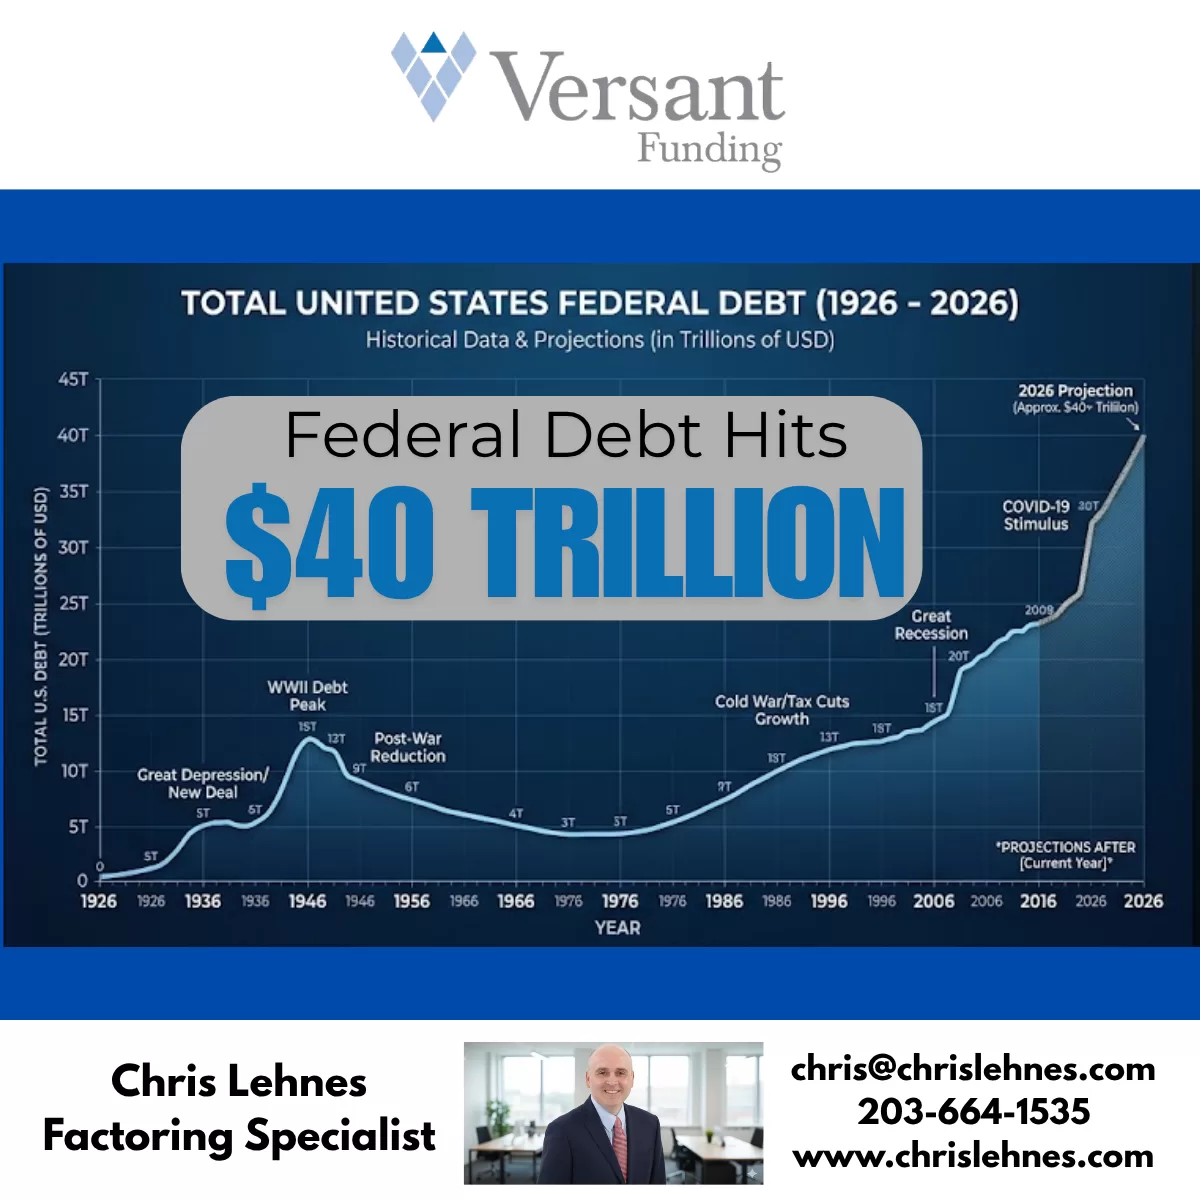
US Debt Reaches $40 Trillion – What Now?

Total U.S. debt has surpassed $40 trillion, a new milestone in the country’s accumulation of budget deficits.

US “total public debt outstanding” officially surpassed $40. trillion according to the U.S. Department of the Treasury.

While that figures is symbolically significant, it is not economically significant. Most investors and economists focus on other metrics, like the Debt to GDP ration, a better sense of an country’s borrowing ability.

But, $40 trillion is a big number, and will draw attention to an unsustainable fiscal trajectory.

Total U.S. debt has surpassed $40 trillion, a new milestone in the country’s accumulation of budget deficits.

Contact Factoring Specialist, Chris Lehnes

Versant Funds $1 Million Non-Recourse Factoring Facility – Service Provider

(August 19, 2026) Versant Funding LLC is pleased to announce that it has funded a $1 Million non-recourse factoring facility for a well-established service providers that works with major hospital systems.

Versant Funding LLC is pleased to announce that it has funded a $1 Million non-recourse factoring facility for a well-established business that provides services to major hospital systems

This private equity-owned company had an imminent, short-term cash need. Its management realized that factoring a subset of their accounts receivable due from financially strong hospitals could be a source of immediate liquidity without requiring their sponsor to invest more capital into the operation.

“Versant can fund faster than most traditional financing sources because we focus solely on the credit quality of our clients’ customers and do not perform a full underwriting or audit of the business” according to Chris Lehnes, Business Development Officer for Versant Funding, and originator of this financing opportunity. “Since this company’s customers include major health networks, we quickly approved the transaction and were able to meet the company’s funding deadline.”  

About Versant Funding

Versant Funding’s custom Non-Recourse Factoring Facilities have been designed to fill a void in the market by focusing exclusively on the credit quality of a company’s accounts receivable. Versant Funding offers non-recourse factoring solutions to companies with B2B or B2G sales from $100,000 to $30 Million per month. All we care about is the credit quality of the A/R. To learn more contact: Chris Lehnes | 203-664-1535 | clehnes@VersantFunding.com

VERSANT FUNDING DEAL ANNOUNCEMENTS
Secured Finance Network
International Factoring Association: Commercial Factor

In the News: Industry publications

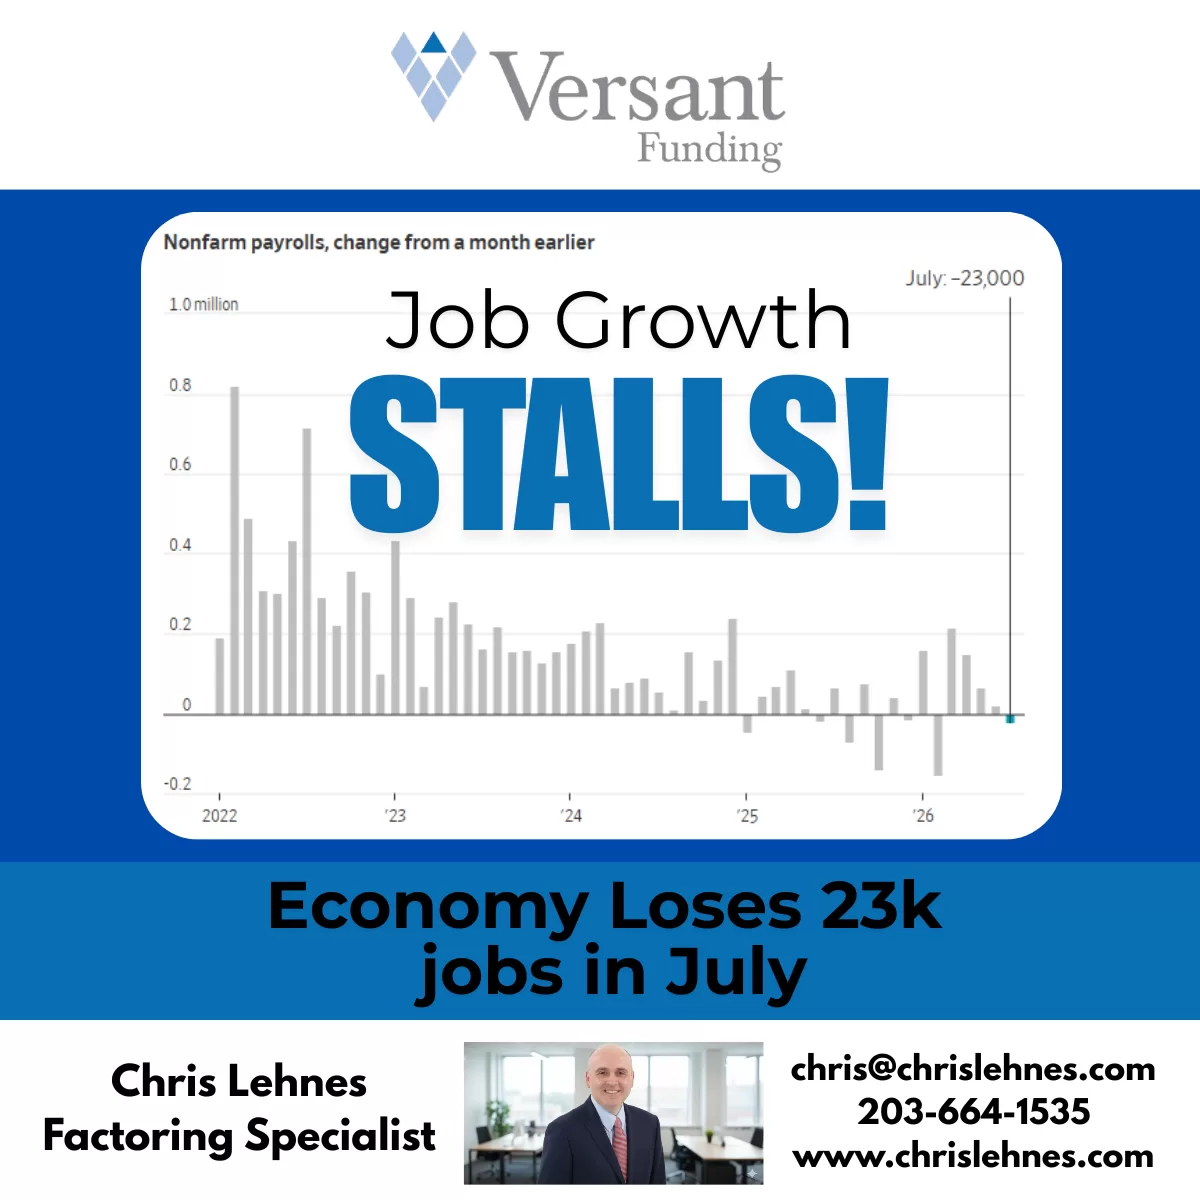
July Job Growth Stalls

Job Growth: The U.S. labor market lost jobs in July, an surprising contraction likely to reignite questions about the economy’s strength when it is also facing elevated inflation.

The latest U.S. Department of Labor report showed that the economy lost 23k jobs in July, a large shortfall undercutting the gain of 83k that economists surveyed by The Wall Street Journal had expected.

Revisions to prior month results showed that the economy added 103k fewer jobs in May and June.

The unemployment rate reduced to 4.1%, from 4.2% in June, even though fewer people were working due to even more individuals existing the workforce.

July Job Growth Stalls

In yet another troubling sign for the labor market, the Bureau of Labor Statistics said that it revised down the prior two months by a combined 103,000. May’s jobs total was cut by 66,000 to 129,000 total jobs added, while June’s total was lowered by 37,000 to a total gain of 57,000.

Economists had been expecting wages to continue pacing at 3.5% from a year ago, but instead wage growth slowed.

“The labor market is stalling again,” wrote Heather Long, chief economist at Navy Federal Credit Union, who called the report “bleak.”

The BLS said employment contracted the most in “local government education,” which declined by 50,000 roles, likely reflecting teachers during summer break. It also flagged a contraction of 19,000 roles in the retail industry. The financial industry shed 14,000 roles.

The agency’s data also showed a 5,000 payroll gain in the manufacturing sector in July and an additional 22,000 roles in construction. These bright spots come as the AI data center boom has benefited some industries, but deeply divided many communities where the centers are located.

Friday’s report likely eases some pressure on the Federal Reserve, which had been widely expected to hike the federal funds rate — potentially as soon as September.

Contact Factoring Specialist, Chris Lehnes