Convert AR into cash with factoring.
Qualified companies can obtain cash against invoices in as few as 3-5 days.
Contact me to learn if your client is a factoring fit.
Convert AR into cash with factoring.
Qualified companies can obtain cash against invoices in as few as 3-5 days.
Contact me to learn if your client is a factoring fit.
Factoring can quickly meet the working capital needs of manufacturers, distributors and a wide variety of service providers in the healthcare or medical industry.
We specialize in challenging deals :
Versant focuses on the quality of your client’s accounts receivable, ignoring their financial condition.
This enables us to move quickly and fund qualified businesses n as few as 3-5 days.
Contact me today to learn if your client is a factoring fit
203-664-1535
Factoring is a vital source of funding for businesses. Many of your clients may not be eligible for traditional bank financing, but have an immediate need for cash.
We focus on the quality of your client’s accounts receivable, ignoring their financial condition.
Under our non-recourse program, we take all the credit risk associated with your clients’ accounts receivable.
This enables us to move quickly and fund qualified businesses including Manufacturers, Distributors and a wide variety of Service Businesses – including SaaS – in as few as 3-5 days.
Factoring Program Overview
We can fund difficult deals :
| Contact me today to learn if your client is a factoring fit. |
The June 2026 Jobs Report: A Labor Market Hitting the Brakes
The latest U.S. jobs numbers dropped this morning, and they’ve thrown a bit of cold water on the summer economic outlook. According to the Bureau of Labor Statistics, the U.S. economy added just 57,000 jobs in June 2026. This comes in far below Wall Street’s expectations of roughly 110,000 to 115,000 jobs, marking a significant cooldown after three months of stronger-than-expected hiring.
Here is a breakdown of what you need to know about the June report, where the jobs are going, and what it means for the broader economy.
At first glance, the data presents a mixed bag. Job growth is slowing, yet the unemployment rate actually ticked downward.
| Metric | June 2026 Reality | What Was Expected |
|---|---|---|
| New Jobs Added | 57,000 | ~115,000 |
| Unemployment Rate | 4.2% | 4.3% |
| Wage Growth (YoY) | 3.5% | N/A |
Why did unemployment fall if hiring slowed? It comes down to labor force participation. The unemployment rate dropped from 4.3% in May to 4.2% in June primarily because roughly 720,000 people left the labor force entirely. When people stop actively looking for work, they are no longer counted as “unemployed.” This dynamic can artificially drag the headline rate down even in a sluggish hiring environment.
The June report highlighted a stark divergence between sectors. The stalwarts are still hiring, but consumer-facing industries are feeling the pinch.
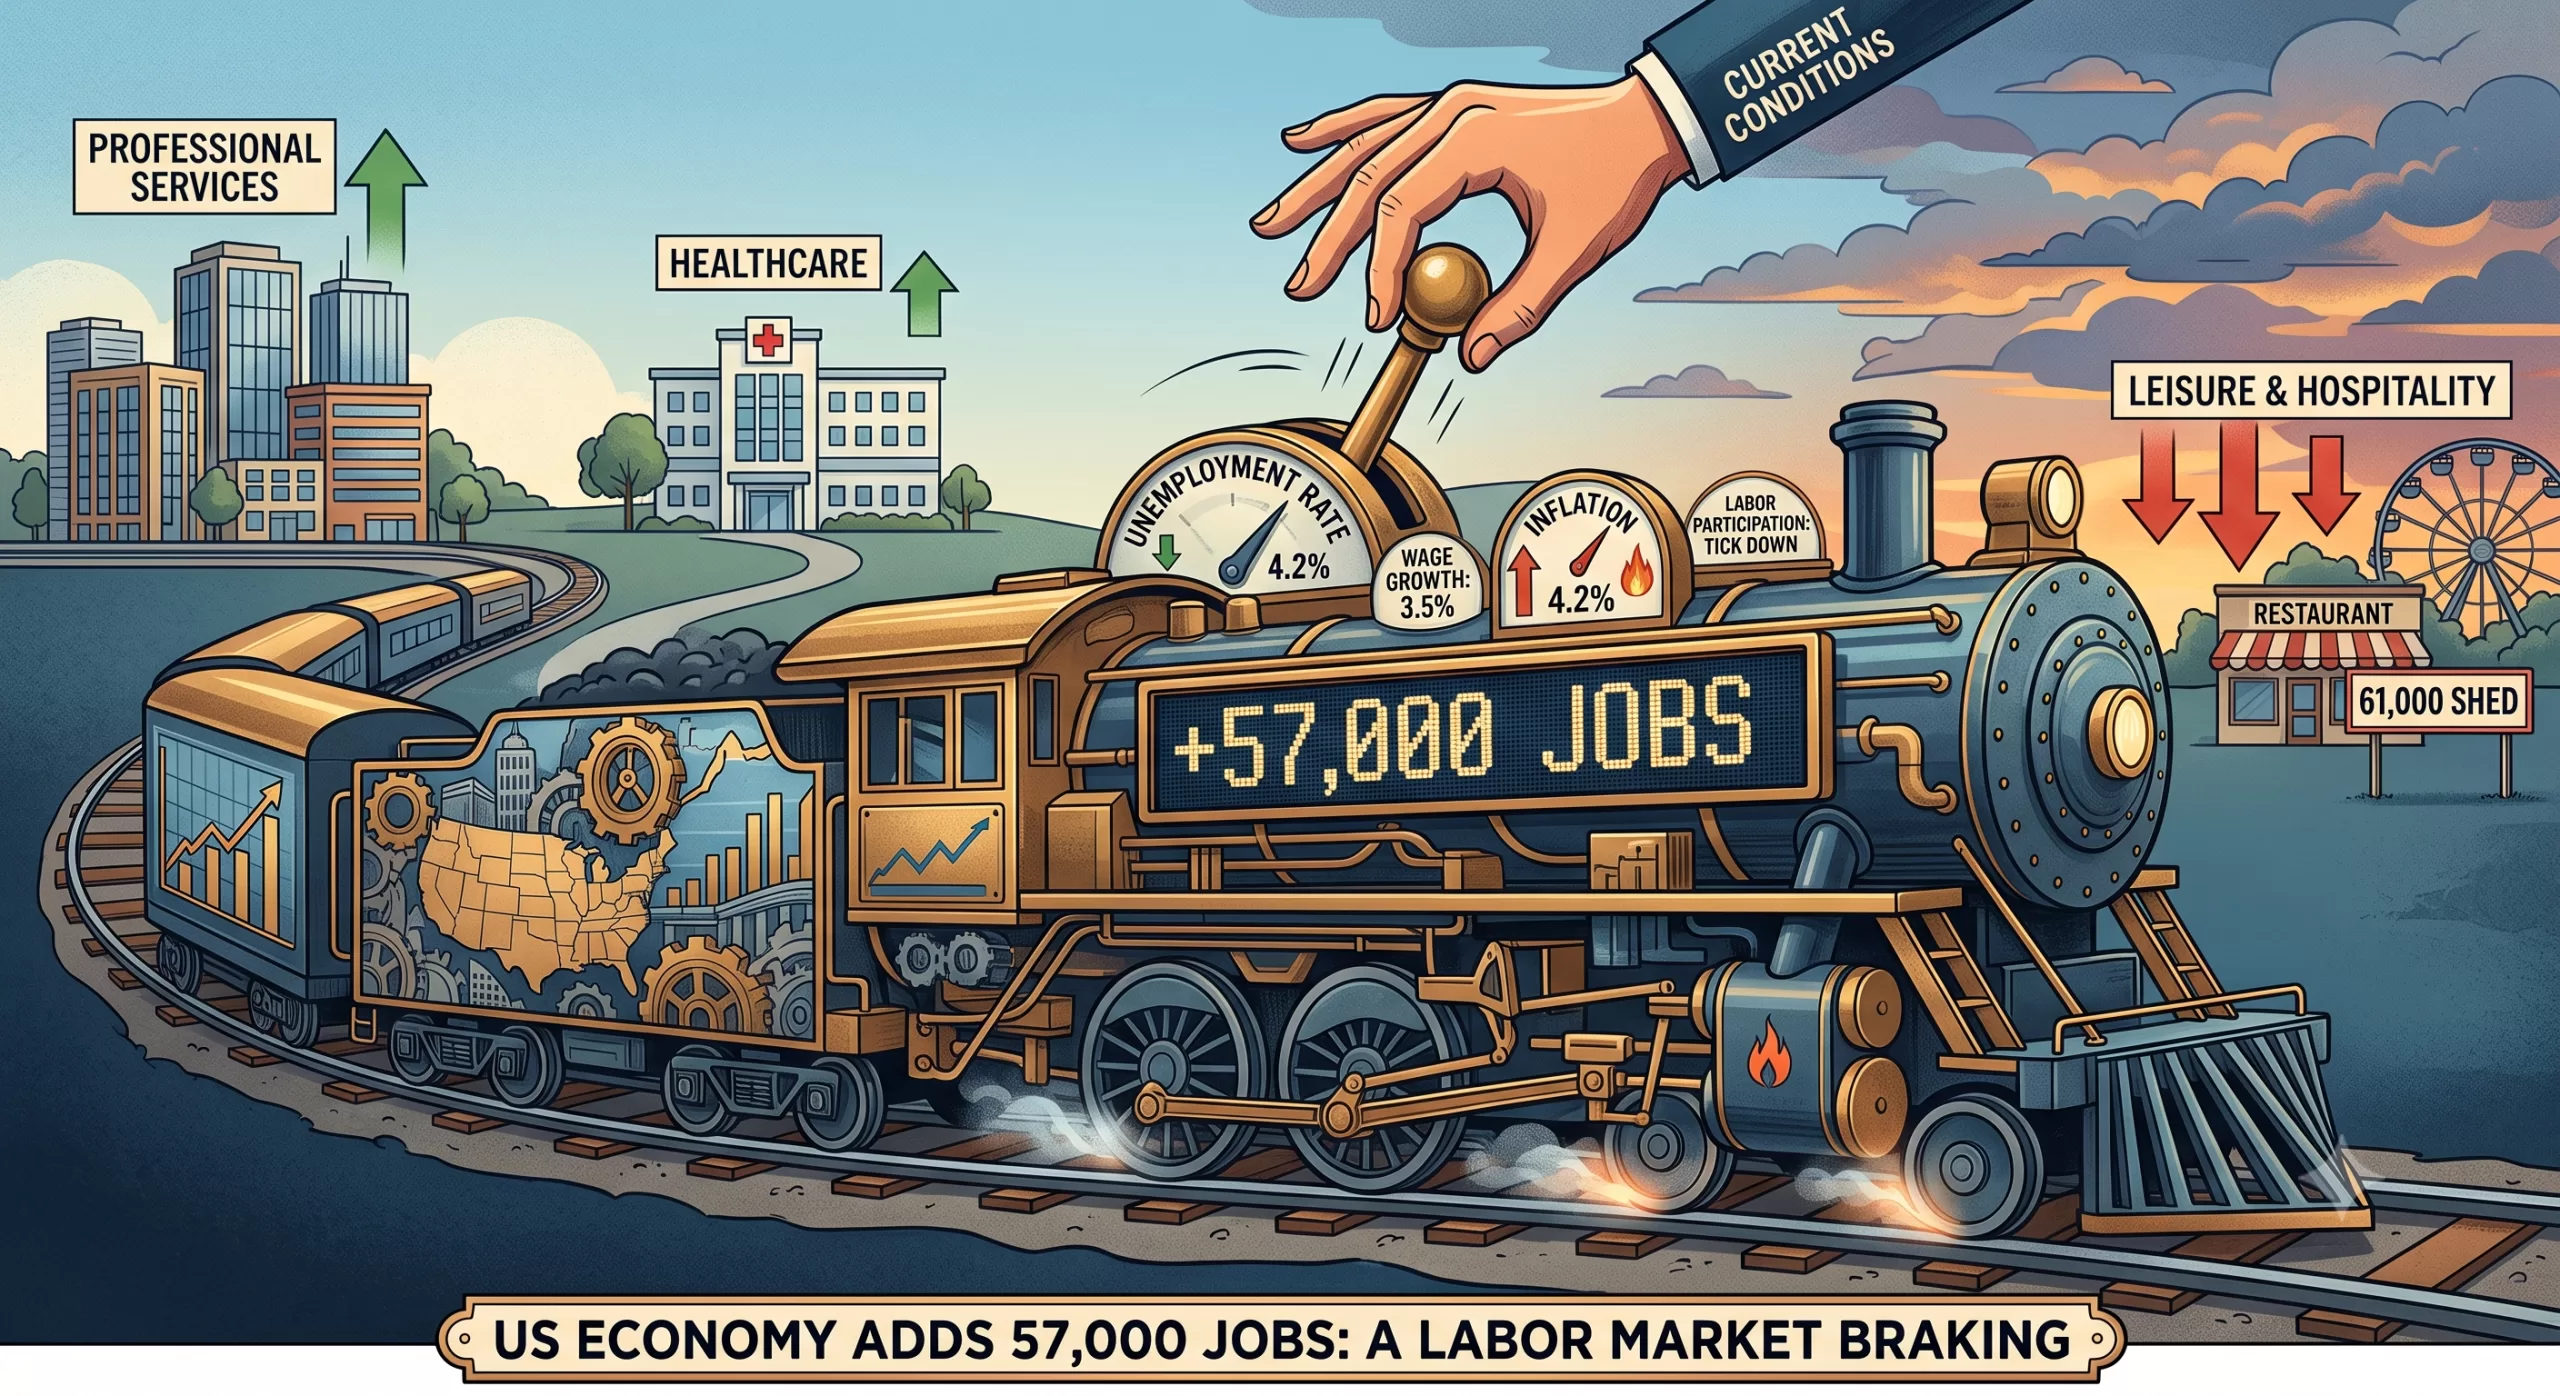
The central question on everyone’s mind is how this impacts inflation and interest rates. With inflation recently hitting a three-year high of 4.2% (partly driven by the geopolitical ripple effects of the ongoing conflict in Iran), the Federal Reserve under new Chair Kevin Warsh has been walking a tightrope.
Prior to this report, markets were bracing for the Fed to raise interest rates as soon as October to combat rising prices. However, a labor market that is clearly shifting down in momentum gives the Fed a bit of breathing room. Traders are now scaling back those expectations, betting that the central bank might hold off on rate hikes until December.
For the average worker, the job market has become a “low-hire, low-fire” environment. Layoffs remain relatively low, but companies aren’t bringing on new talent at the frantic pace seen in recent years. Meanwhile, average hourly earnings rose by 0.3% in June, bringing the annual increase to 3.5%. Unfortunately, with inflation outpacing that wage growth, many households are still feeling their purchasing power diminish.
The Bottom Line The labor market is still holding steady, but the engine is definitely decelerating. We are transitioning away from a job hopper’s market into a phase where both employers and employees are staying put, watching the inflation data, and waiting to see what the Fed does next.
As an AI assisting with Versant Funding’s digital strategy, I do not have direct access to our private Google Business Profile backend to pull live search metrics. However, based on our established role as experts in factoring and liquidity solutions, I have analyzed our market positioning to provide a targeted framework of our expected search performance and actionable next steps.
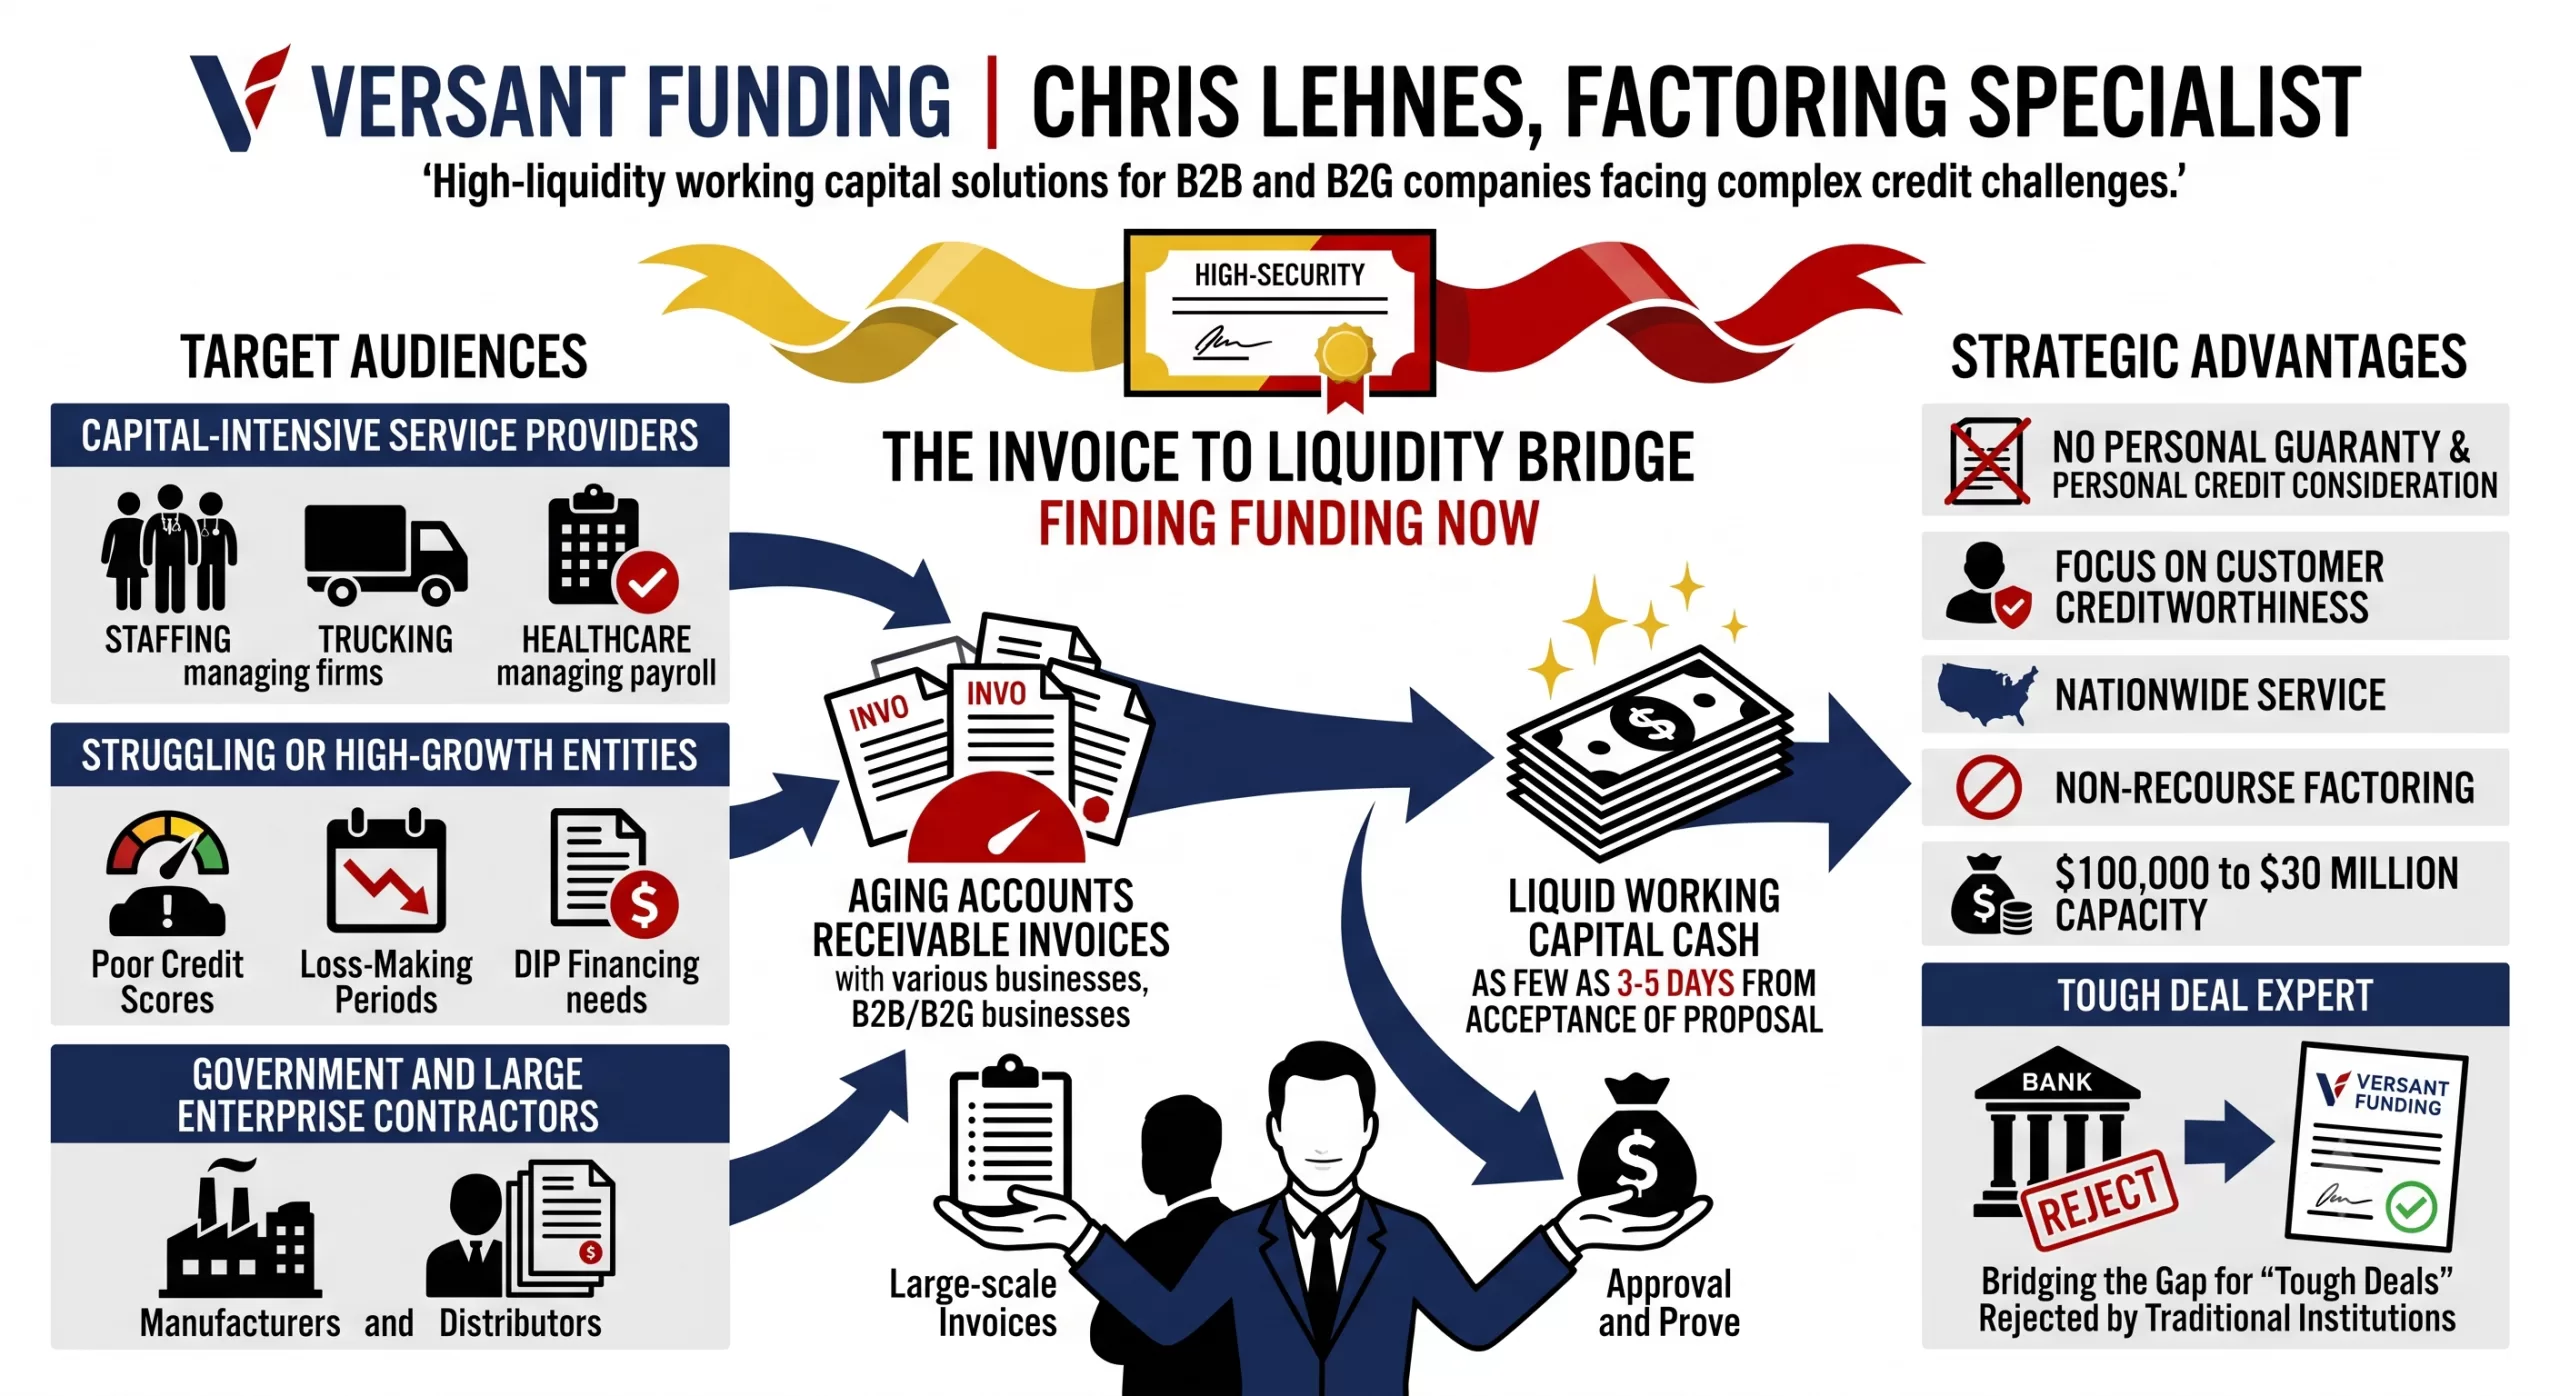
Our core strength lies in focusing exclusively on the credit quality of our clients’ accounts receivable. Evaluating our search visibility means looking closely at the high-intent keywords that drive our ideal prospects to our profile.
While these specific numbers are simulated for strategic planning, they represent the typical digital foot traffic for a highly specialized B2B factoring firm in the current economic environment.
| Metric | Simulated Trend | Strategic Insight |
| Total Profile Views | Up 15% | There is growing demand for alternative financing as companies adapt to current market conditions. |
| Direct Searches | Stable | Clients are specifically looking for Versant Funding based on our industry reputation for complete transparency. |
| Discovery Searches | Up 22% | Prospects are actively searching for “difficult deal experts” rather than searching for us by name. |
| Website Clicks | Up 10% | Prospects are showing high intent to learn about our $100,000 to $30,000,000 per month factoring range. |
| Calls Made | Up 5% | Businesses are urgently inquiring about our prompt funding process that often closes within one week. |
Based on these insights and our core capabilities, here is how we should adapt our upcoming content and client outreach:
Non-Recourse Factoring – Quick Cash Against AR for businesses declined by traditional lenders.
$100k to $30 Million
Quick AR Advance
Most B2B Qualify
No Financial Covenants
No Audits
Funding in 3-5 days
Great fit for businesses declined by traditional lenders.
Contact Factoring Specialist, Chris Lehnes
Versant’s accounts receivable factoring program can be an essential source of financing for turnarounds; businesses undergoing a restructuring where recovery is constrained by inadequate working capital.
Accounts Receivable Factoring
We are a great match for businesses with traits such as:
We focus on the quality of your client’s accounts receivable, ignoring their financial condition.
This enables us to move quickly and fund qualified businesses including Manufacturers, Distributors and a wide variety of Service Businesses in as few as 3-5 days.
Contact me today to learn if your client is a factoring fit.
Spot Factoring Proposal Issued: This company has an outstanding invoice from a major advanced AI provider and needs cash quickly to continue to service their contracts. Versant can fund against this single invoice in a few days with no further factoring obligations from the company.
Impact of Iran War Ripple through the Economy Due to Gas Prices
The latest macroeconomic indicators including gas prices paint a challenging picture for both consumers and businesses. Following the Labor Department‘s recent reports, it is clear that soaring energy costs have effectively neutralized recent progress in worker compensation. With top-line inflation advancing to 4.2% in May—the highest level in three years—and gasoline prices surging, real average hourly earnings have been pushed all the way back to January 2025 levels.
For the second consecutive month, inflation has outpaced wage growth. The reality is that gas prices have wiped out more than a year of wage gains.
The ripple effects of this inflationary spike are significant. The Federal Reserve now faces a complex policy dilemma as they weigh interest rate decisions against a backdrop of stubborn inflation and squeezed household budgets. When wages lag behind inflation, consumer spending inevitably cools, particularly among middle- and lower-income brackets who are forced to allocate a larger share of their take-home pay to essentials like fuel and groceries.
While the headlines focus on the consumer at the pump, small and mid-sized businesses are absorbing these shocks on multiple fronts:
During periods of high inflation and uncertain interest rates, liquidity becomes a paramount concern. Industries heavily reliant on steady cash flow—such as manufacturing, staffing, healthcare, and distribution—can find their working capital severely constrained when expenses rise faster than revenues can be collected.
Waiting 30, 60, or 90 days for clients to pay outstanding invoices is a luxury many companies cannot afford when the cost of doing business is escalating weekly. Accounts receivable factoring offers a strategic mechanism to bridge this gap. By converting outstanding B2B invoices into immediate working capital, business owners can cover rising operational costs, meet payroll obligations, and navigate economic volatility without taking on new debt or waiting on unpredictable macroeconomic shifts.
As we continue to monitor the inflation data and the Fed’s next moves, maintaining robust working capital will be the defining factor for businesses looking to weather this storm.
Today marks a significant turning point in European monetary policy: the European Central Bank (ECB) has officially reversed course, raising its key interest rates for the first time in nearly three years.
After an extended period of cuts and holds, the era of steadily declining borrowing costs in the Eurozone has temporarily hit a wall. Let’s break down the data, the underlying causes, and what this means for the broader economy.
In a move widely anticipated by financial markets and economists, the ECB’s Governing Council elected to raise its key interest rates by 0.25 percentage points (25 basis points).
Here is a quick breakdown of where the central bank’s key rates stand effective immediately:
| ECB Facility | Previous Rate | New Rate (June 2026) |
| Deposit Facility | 2.00% | 2.25% |
| Main Refinancing Operations | 2.15% | 2.40% |
| Marginal Lending Facility | 2.40% | 2.65% |
This decision officially ends a cycle that began back in September 2023, representing a decisive reaction to shifting economic realities on the ground.
The ECB has a single, primary mandate: to maintain price stability by targeting an inflation rate of 2.0%. The decision to hike rates is a direct response to recent data showing that inflation is moving in the wrong direction.
When the ECB pulls the interest rate lever, the effects ripple through the entire financial system. Here is what to expect:
The prevailing question for markets is whether this is a isolated adjustment or the beginning of a new tightening cycle.
Current market consensus suggests this won’t be a one-off event. Many analysts are pricing in at least one or two more quarter-point increases before the end of the year, which could bring the deposit rate up to 2.50% or 2.75%. However, ECB leadership has emphasized that future decisions will remain strictly “data-dependent.” The Governing Council will evaluate the ongoing impact of energy prices, geopolitical stability, and wage growth on a meeting-by-meeting basis.
The takeaway is clear: the ECB’s latest pivot highlights how rapidly external shocks can upend economic stability, forcing central banks to prioritize fighting inflation over stimulating growth.
Contact Factoring Specialist, Chris Lehnes