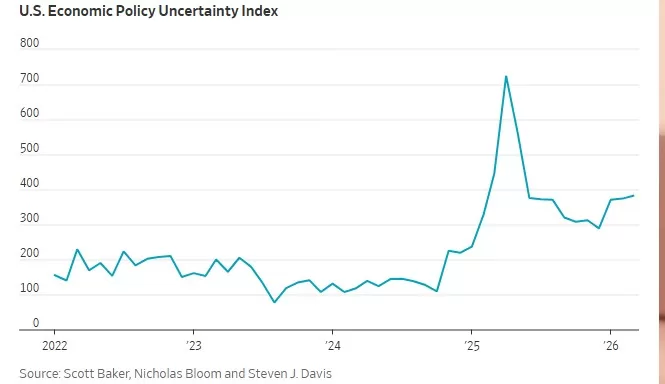
If the global economy feels like a high-wire act lately, you aren’t alone. We are currently navigating a “polycrisis“—a fancy term for when multiple major headaches (inflation, geopolitical tension, and shifting labor markets) all hit the fan at the same time.
We are standing on a narrow ledge. One side leads to a hard landing; the other leads to a stabilized “new normal.” Here is a look at the forces threatening to push us off, and the safety nets that might just pull us back.
The Push: What Could Tip Us Over?
It doesn’t take a wrecking ball to cause a recession; sometimes, it just takes a few well-placed dominos. Here are the primary risks:
The “Higher for Longer” Fatigue: While central banks use interest rates to cool inflation, keeping them elevated for too long puts immense pressure on household debt and corporate margins. If the “lag effect” hits all at once, consumer spending—the engine of the economy—could stall.
Geopolitical Aftershocks: Energy prices are notoriously sensitive to global conflict. Any significant escalation in major trade corridors can reignite supply chain chaos, sending the cost of goods back into the stratosphere.
The Commercial Real Estate Ghost Town: With remote work now a permanent fixture, many office buildings are sitting half-empty. As these property loans come due for refinancing at higher rates, we could see a localized banking tremor.
The Pull: What Could Help Us Pull Through?
It’s not all doom and gloom. There are several structural “muscles” keeping the economy upright:
The Resilient Labor Market: Despite tech layoffs making headlines, overall unemployment remains historically low. As long as people have jobs, they tend to keep spending, which provides a powerful floor for the economy.
The Productivity “AI Bump”: We are at the beginning of a massive technological shift. Early adoption of generative AI is already beginning to streamline workflows and reduce operational costs, which could lead to a non-inflationary growth spurt.
Household Balance Sheets: Unlike the 2008 crash, many consumers and corporations locked in low interest rates years ago. This “debt buffer” has bought the private sector time to adjust to the new economic reality.
The Bottom Line: Balance, Not Freefall
The economy isn’t necessarily “broken,” but it is transitioning. We are moving away from an era of “free money” and into an era where efficiency and strategic investment matter again.
Scenario
Key Driver
Likely Outcome
The Hard Landing
Persistent inflation + high rates
Brief but sharp recession; rising unemployment.
The Soft Landing
Controlled cooling + tech growth
Flat growth for a year, followed by a steady recovery.
The No Landing
Continued high spending
Economy stays hot, but rates stay high indefinitely.
The Takeaway: While the ledge is narrow, the path across is still visible. Navigating the next twelve months will require agility from policymakers and patience from investors. We may be on the edge, but we aren’t over it yet..
Press Release: (March 26, 2026) Versant Funding LLC is pleased to announce that it has funded a $1.4 Million non-recourse factoring facility to a manufacturer of equipment used by global auto companies.
While our newest client has successfully secured contracts with some of the world’s largest manufacturers, slow-paying accounts receivable are putting pressure on the company’s cash flow and preventing them from taking on new business.
“In evaluating a funding opportunity, Versant focuses exclusively on the quality of our client’s accounts receivable” according to Chris Lehnes, Business Development Officer for Versant Funding, and originator of this transaction. “Since this company’s customers are among the strongest on the planet, our facility will essentially have no cap and will grow automatically as the company’s AR balances increase, providing our client the cash needed to expand.”
About Versant Funding: Versant Funding’s custom Non-Recourse Factoring Facilities have been designed to fill a void in the market by focusing exclusively on the credit quality of a company’s accounts receivable. Versant Funding offers non-recourse factoring solutions to companies with B2B or B2G sales from $100,000 to $30 Million per month. All we care about is the credit quality of the A/R. To learn more contact: Chris Lehnes|203-664-1535 | chris@chrislehnes.com
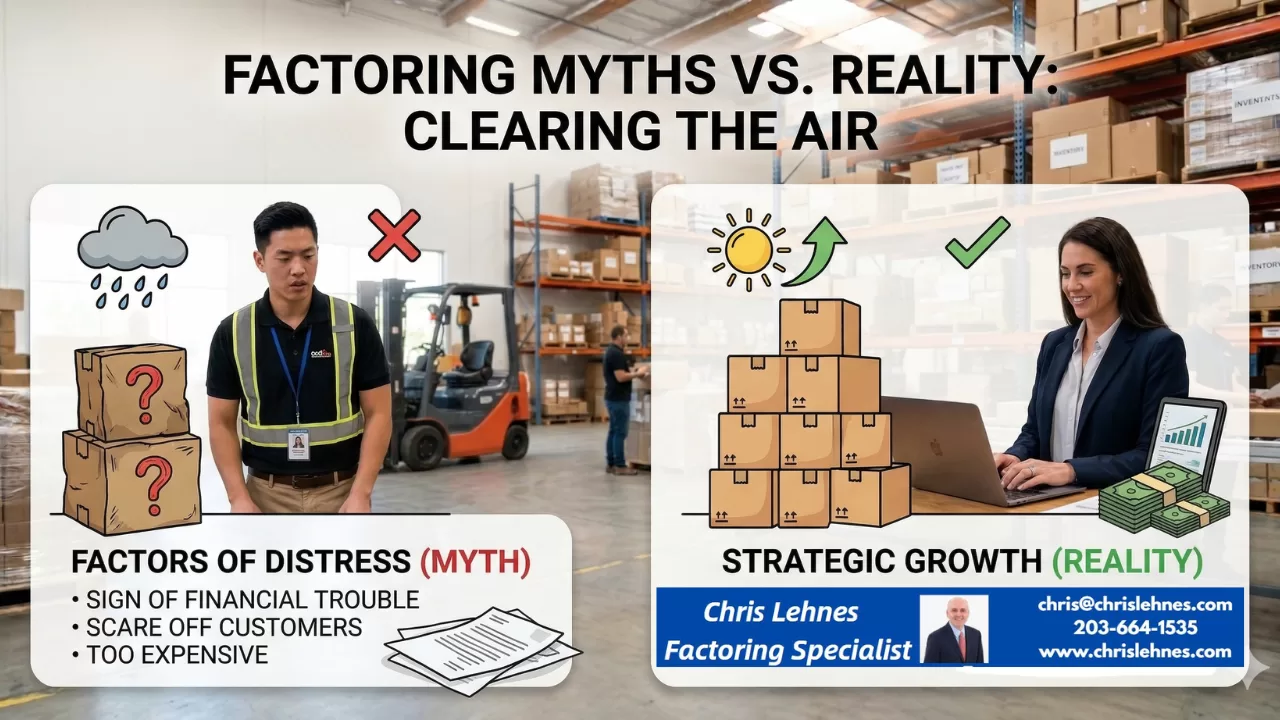
For many distributors, the word “factoring” carries some outdated baggage. If you’re hesitant to pull the trigger, it’s likely because of one of these common misconceptions. Let’s separate the noise from the facts:
The Myth
The Reality
“Factoring is a sign of financial trouble.”
Factoring is a sign of growth. Most companies use factoring because they are growing too fast for their cash flow to keep up. It’s a strategic choice to fuel expansion, not a last-ditch effort to stay afloat.
“My customers will think I’m going under.”
It’s a standard B2B practice. Major retailers and manufacturers deal with factors every day. In many industries, like apparel or electronics distribution, it’s actually the “gold standard” for managing receivables.
“It’s way too expensive.”
Look at the ROI. While the fee (1–3%) is higher than a bank loan, the “cost of waiting” 60 days for a check often means missing out on new inventory or early-pay discounts from your own suppliers that could actually save you more than the factoring fee.
“I’ll lose control of my customer relationships.”
You stay in the driver’s seat. Modern factoring companies act as a professional extension of your back office. They want your customers to stay happy so they keep buying (and paying). You still manage the sales and service; they just handle the math.
“It’s just like a high-interest loan.”
It’s not a loan at all. Because you are selling an asset (your invoice), you aren’t taking on debt. There are no monthly principal or interest payments to worry about—the “payment” comes from your customer, not your bank account.
The “Silent” Benefit: Professional Credit Checks
One “Reality” that distributors often overlook is that a factor acts as a free credit department. Before you ship $50,000 worth of goods to a new client, you can ask your factor to check their credit. If the factor won’t buy the invoice, that’s a massive red flag that you probably shouldn’t be selling to that customer on terms in the first place.
What you should know in selecting a factoring Partner
Choosing a factoring company is like choosing a long-term business partner. The right one will act as your back-office credit department; the wrong one can be an expensive administrative nightmare. Use this checklist to vet potential partners:
1. The Core Logistics
[ ] Industry Expertise: Do they have experience with the specific nuances of distribution (e.g., handling chargebacks, bill-backs, or progressive shipping)?
[ ] Advance Rate: Will they advance at least 80–90% of the invoice value?
[ ] Funding Speed: Can they provide “Same Day” or “Next Day” funding once an invoice is verified?
[ ] Funding Source: Are they a Direct Lender (bank-backed) or an independent factor? (Direct lenders often have lower rates and more stability).
2. Transparency & Fees
[ ] The “All-In” Rate: Ask for a breakdown of all fees. Look out for hidden “junk fees” like application fees, wire fees, or credit check fees.
[ ] Recourse vs. Non-Recourse: * Recourse: You must buy back the invoice if your customer doesn’t pay. (Lower fees).
Non-Recourse: The factor takes the credit risk if the customer goes bankrupt. (Higher fees).
[ ] Volume Requirements: Are there “Monthly Minimums”? If you don’t hit a certain volume, will you be penalized?
3. The “Relationship” Factor
[ ] Dedicated Account Manager: Will you have a single point of contact who knows your business, or a generic 1-800 help desk?
[ ] Customer Interaction Style: How do they contact your customers for verification? You want a partner who is professional and polite, as they represent your brand.
[ ] Technology Integration: Do they sync with your accounting software (QuickBooks, NetSuite, etc.) for easy invoice uploading?
4. Contract Flexibility
[ ] Contract Length: Avoid multi-year lock-ins. Look for month-to-month or one-year terms with clear exit clauses.
[ ] Termination Notice: How much notice is required to leave? (Usually 30–90 days).
[ ] Personal Guarantee: Is a personal guarantee required? (Standard for many small business factors, but worth clarifying).
What is Factoring: In the world of distribution, the “growth paradox” is a real headache. You land a massive new retail contract—which is great news—but suddenly you’re shelling out for inventory and shipping costs while your customer sits on a 60- or 90-day payment term.
For many distributors, waiting for those invoices to clear creates a suffocating bottleneck. This is where Accounts Receivable (AR) Factoring comes in. It’s not a loan; it’s a financial tool that turns your unpaid invoices into immediate working capital.
How It Works: The Quick Breakdown
Instead of waiting months for a customer to pay, you sell your outstanding invoices to a “factor” (a specialized financial company).
The Advance: The factor typically advances you 80% to 90% of the invoice value within 24 hours.
The Collection: The factor handles the collection from your customer.
The Rebate: Once the customer pays, the factor sends you the remaining balance, minus a small fee (usually 1–3%).
4 Major Benefits for Distributors
1. Bridge the Inventory Gap
Distributors often have to pay suppliers long before they get paid by their own clients. Factoring provides the liquidity to pay your manufacturers upfront, often allowing you to take advantage of early-payment discounts that can actually offset the cost of the factoring fee itself.
2. Fuel Rapid Scalability
Traditional bank loans are limited by your credit history or collateral. Factoring, however, scales with your sales. The more you sell to reputable customers, the more funding becomes available. It allows you to say “yes” to large orders that you otherwise couldn’t afford to fulfill.
3. Professional Credit Management
Many factoring companies act as an extension of your back office. They perform credit checks on your potential customers, helping you avoid “bad seeds” before you ship a single pallet. This reduces your risk of bad debt and saves your team the awkwardness of making collection calls.
4. No New Debt
Since factoring is the purchase of an asset (your invoice) rather than a loan, it doesn’t show up as debt on your balance sheet. This keeps your debt-to-equity ratio clean, making your business look much healthier to future investors or traditional lenders.
Is It Right For You?
Factoring is particularly powerful if you are:
A startup with a thin credit history but blue-chip customers.
Experiencing seasonal spikes that drain your cash reserves.
Tired of the “waiting game” associated with 30, 60, or 90-day terms.
While there is a cost involved, the ability to reinvest that cash immediately into new inventory or operations often outweighs the fee. In the fast-moving world of distribution, speed is a competitive advantage.
Factoring vs. A Traditional Line of Credit: A Distributor’s Comparison
While both tools solve cash flow problems, they operate very differently. Here is how they stack up for a growing distributor:
Feature
AR Factoring
Traditional Bank Line of Credit (LOC)
Funding Limit Based On…
The creditworthiness of your customers and your accounts receivable balance.
Your business’s credit history, profitability, and your collateral.
Speed of Funding
Extremely fast. Setup takes a few days; once active, funding often occurs within 24–48 hours of invoice verification.
Slow. The approval process can take weeks or even months.
Debt Type
Not Debt. It is the “asset purchase” of your invoices.
Debt. This is a loan that appears as a liability on your balance sheet.
Impact on Credit
Boosts Credit Score. It provides cash to pay your suppliers and operational debts on time.
Lowers “Available” Credit. Utilizing the full LOC can temporarily lower your score until it’s paid down.
Administrative Support
The factor often provides credit management and collection services, freeing up your back office.
You retain full responsibility for all collections and monitoring customer credit.
Scalability
Unlimited. As your credit-worthy sales grow, your available funding automatically increases.
Capped. Your limit is fixed and requires a re-application process to increase.
Gemini said
Certainly. Here is a comparison table and a section you can drop directly into your blog post.
Factoring vs. A Traditional Line of Credit: A Distributor’s Comparison
While both tools solve cash flow problems, they operate very differently. Here is how they stack up for a growing distributor:
Feature
AR Factoring
Traditional Bank Line of Credit (LOC)
Funding Limit Based On…
The creditworthiness of your customers and your accounts receivable balance.
Your business’s credit history, profitability, and your collateral.
Speed of Funding
Extremely fast. Setup takes a few days; once active, funding often occurs within 24–48 hours of invoice verification.
Slow. The approval process can take weeks or even months.
Debt Type
Not Debt. It is the “asset purchase” of your invoices.
Debt. This is a loan that appears as a liability on your balance sheet.
Impact on Credit
Boosts Credit Score. It provides cash to pay your suppliers and operational debts on time.
Lowers “Available” Credit. Utilizing the full LOC can temporarily lower your score until it’s paid down.
Administrative Support
The factor often provides credit management and collection services, freeing up your back office.
You retain full responsibility for all collections and monitoring customer credit.
Scalability
Unlimited. As your credit-worthy sales grow, your available funding automatically increases.
Capped. Your limit is fixed and requires a re-application process to increase.
Which One Wins for Distributors?
A bank line of credit is almost always the cheapest form of capital if you can get approved for a large enough limit.
However, for distributors in a hyper-growth phase, or those whose balance sheets don’t match their ambition, AR factoring offers unmatched speed and scalability. It allows you to leverage your customers’ financial strength to fund your own growth.
The Final Verdict: When to Choose Factoring
For a distributor, the choice between factoring and other financing boils down to your growth trajectory and customer base.
A traditional bank line of credit is often the lowest-cost option, but it is also the most rigid. If you have years of steady profitability and a “boring” (predictable) growth curve, the bank is your best friend.
However, AR factoring is the superior choice if:
You are growing faster than your cash flow allows: If a sudden 50% increase in orders would actually break your business because you can’t afford the inventory, you need factoring.
You have “lumpy” revenue: If you deal with seasonal spikes where you need $500k in October but only $50k in January, the flexibility of factoring is unmatched.
Your customers are larger than you: If you are a small distributor selling to giants like Walmart or Amazon, a factor will look at their multi-billion-dollar credit rating to fund you, rather than your own limited history.
Ultimately, factoring isn’t just a way to get paid early—it’s a way to weaponize your accounts receivable to outmaneuver competitors who are still stuck waiting for a check in the mail.
(March 19, 2026) Versant Funding LLC is pleased to announce that it has funded a $5 Million non-recourse factoring facility to a 90+ year-old company that provides services to major consumer brands.
After acquisition by a Private Equity Group, our latest client’s new management team implemented a turnaround plan which required additional cash. While the company was in the process of applying for an asset-based line of credit, time was of the essence and a funding date for the ABL facility was uncertain.
“Versant can fund faster than most traditional financing sources because we focus solely on the credit quality of our clients’ customers and do not perform a full underwriting or audit of the business” according to Chris Lehnes, Business Development Officer for Versant Funding, and originator of this financing opportunity. “Since this company’s customers include some of the world’s strongest consumer brands, we quickly approved the transaction and were ready to fund in about a week.”
Versant Funding’s custom Non-Recourse Factoring Facilities have been designed to fill a void in the market by focusing exclusively on the credit quality of a company’s accounts receivable. Versant Funding offers non-recourse factoring solutions to companies with B2B or B2G sales from $100,000 to $30 Million per month. All we care about is the credit quality of the A/R. To learn more contact: Chris Lehnes |203-664-1535 | chris@chrislehnes.com
The first few warm days of spring mean flowers, baseball, and for many small business owners in March 2026, the annual financial checkup. If you’ve looked at your numbers and realized you need a cash injection for new equipment, that third location, or an aggressive inventory build, you know the drill: It’s time to find the capital. While large national banks are the obvious choice, they are often difficult, impersonal, and slow. By comparison, credit unions have become the unexpected superstars of commercial lending, especially for small and medium-sized enterprises (SMEs).
If you are hunting for a business loan this month, you need to understand why credit unions are dominating and how to find the one that will actually make that critical “yes” happen for your business.
The Not-So-Secret Advantage of the Member-Owner
To understand why credit unions often beat banks on business lending, you have to look at their structure.
Banks answer to shareholders who demand profits and high returns on equity. Every decision, including who gets a loan, is filtered through the lens of maximizing shareholder value.
Credit unions, however, are not-for-profit cooperatives. They do not have public stock. Their members (you, me, and other account holders) are the owners.
This single difference ripples through every interaction. For business lending in 2026, it means:
1. Rates and Fees That Just Make More Sense: Instead of returning profit to Wall Street, credit unions reinvest earnings back into the institution and their members. This often manifests as lower interest rates on commercial loans and significantly lower loan-origination and maintenance fees. In 2026, when inflation has been a recent headache, a difference of 0.5% on a large loan term can mean thousands of dollars saved.
2. Hyper-Local Expertise: When you sit down with a commercial lender at a bank, their rules, algorithms, and models might be set at headquarters 2,000 miles away. They may not understand the specific micro-market in Newtown, Connecticut, where you are operating. But your local credit union officer lives here. They understand why opening a second pizza parlor on the new development is a smart bet, not a risky venture. They lend based on local market knowledge.
3. Relationships Over Risk-Scores: A bank will look at your credit score and financial statements, enter them into a model, and receive a automated “Approve” or “Deny.” Credit unions, especially smaller, focused ones, prioritize relationships. They are more likely to have a real human look at your complete business plan, understand your unique vision, and listen to the story behind your application, not just the numbers on the page.
The “New Reality” of SBA Lending
One of the most important developments in 2026 is that the Small Business Administration (SBA) has made it significantly easier and faster for credit unions to facilitate SBA 7(a) and 504 loans.
For many small businesses, these government-backed loans are the Holy Grail: long terms, lower interest rates, and lower down-payment requirements. Previously, massive banks dominated this space because the paperwork was crushing.
However, the “Streamline and Connect Act” of 2024 (as we projected) drastically simplified the SBA application process and created digital interfaces specifically designed for smaller community financial institutions.
This means that in March 2026, the local credit union you never expected to handle an SBA application is now a Preferred Lender, capable of getting your government-backed loan approved in weeks, not months.
How to Evaluate a Credit Union in March 2026
You can’t just walk into the nearest credit union and expect a perfect loan offer. To find the “best” one for your business right now, you must be strategic:
Step 1: Membership Criteria (The Gateway)
Credit unions can’t just lend to anyone. They operate under a specific “field of membership” (FOM). While some have broadened their charters, many are still strictly limited. To find the “best,” you must find the one you can actually join.
Geographic FOM: Are you eligible because your business is located in Newtown, CT, or the surrounding county? This is the most common path.
Associational or Professional FOM: Are you a veteran? An educator? A first responder? A member of a specific local church or union? There are niche credit unions specialized for these groups, and they often offer highly beneficial industry-specific lending programs.
Step 2: Technology and Speed
While personal relationships are the hallmark of credit unions, it’s 2026. You should not have to wait 30 days for a response to your application. A strong, business-friendly credit union will have a fast, streamlined digital application portal.
They should have digital tools that connect directly to your accounting software (like QuickBooks or Xero), allowing their lenders to instantly verify your cash flow without forcing you to hunt down piles of paper bank statements. If a credit union’s website looks like it hasn’t been updated since 2018, that is a massive red flag.
Step 3: Ask About Specific Business Expertise
The credit union that is excellent for a car loan or a personal mortgage is not necessarily the best choice for a $500,000 commercial line of credit to finance inventory for a manufacturing business.
When you interview a prospective credit union, ask about their experience in your industry. A credit union that specializes in healthcare practice lending will have different perspectives and better loan structures than one that primarily works with general contractors.
The March 2026 Takeaway: Don’t Lead with a Bank
Your default shouldn’t be the massive financial conglomerate that you can only reach via an 800-number. Your first stop in 2026 should be your local, community-focused credit union. They are built to serve owners like you, and they have the tools and local knowledge to help your business take flight this spring.
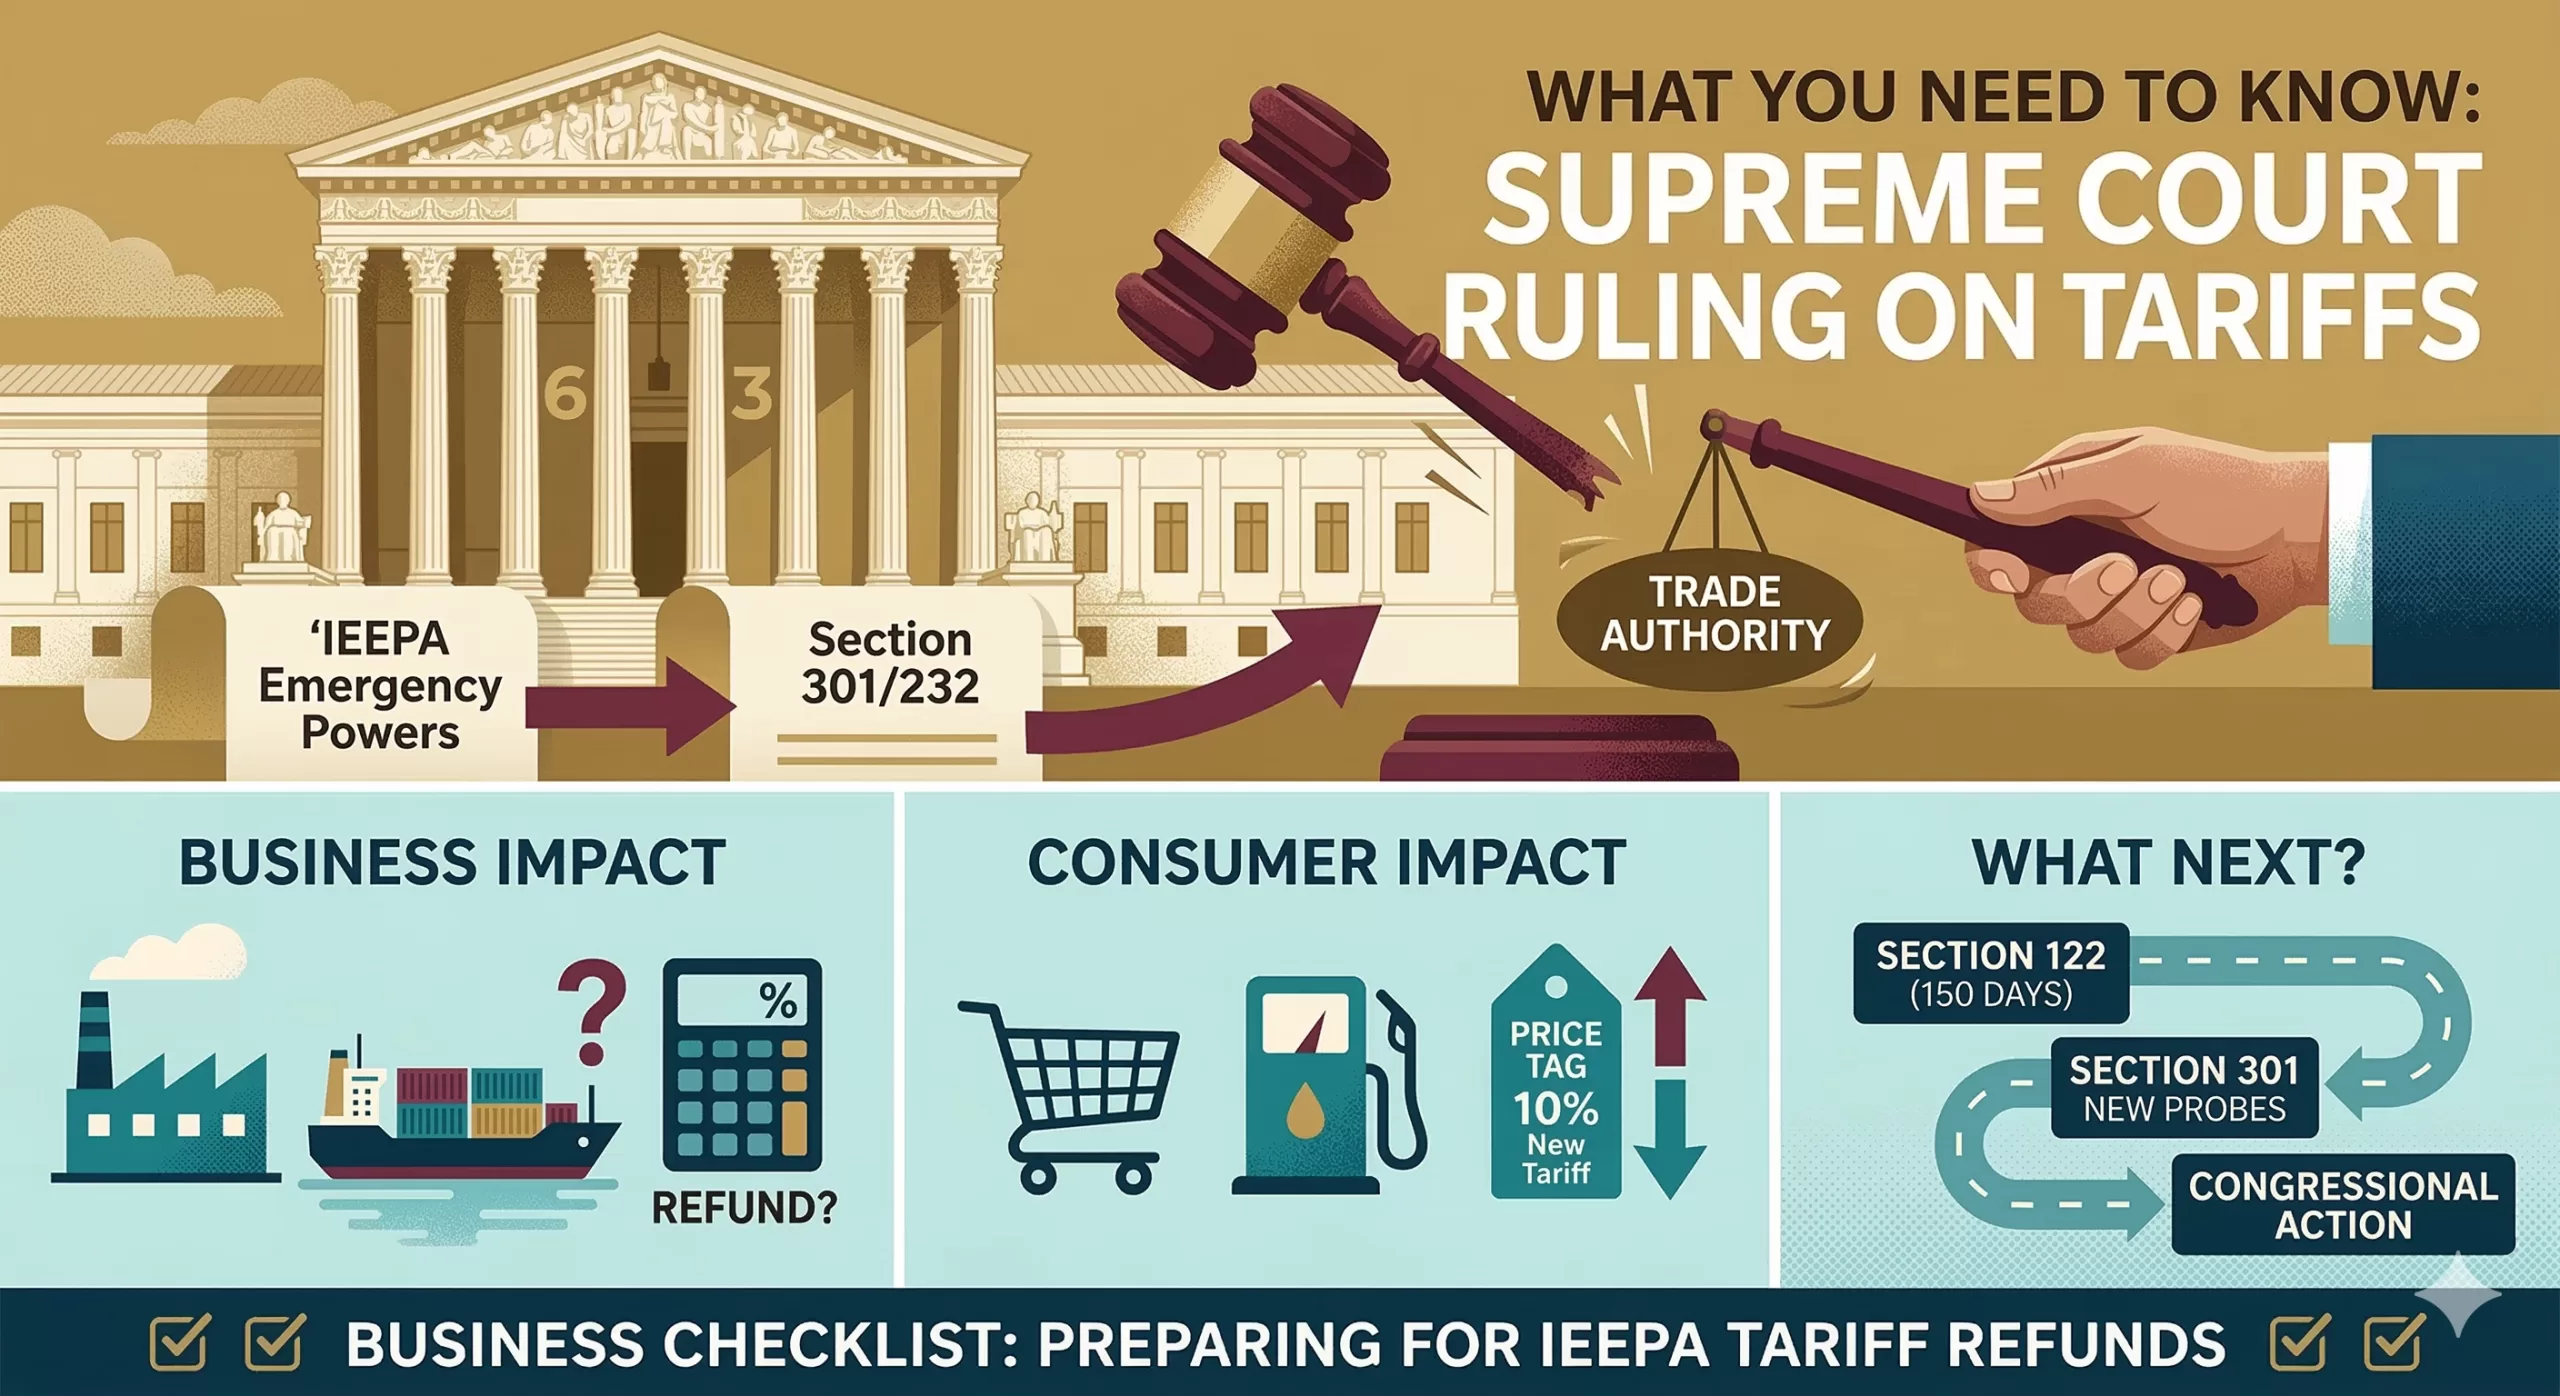
In a landmark decision that has reshaped the landscape of IEEPA Tariffs and American trade policy, the Supreme Court recently issued a ruling in Learning Resources, Inc. v. Trump. The 6-3 decision struck down a series of sweeping tariffs, delivering a significant blow to the administration’s use of emergency powers to regulate the economy.
If you’re a business owner, importer, or simply a consumer wondering why prices are shifting again, here is everything you need to know about this historic ruling about IEEPA Tariffs and what comes next.
The Heart of the Case: IEEPA Tariffs vs. The Taxing Power
The central question before the Court was whether the International Emergency Economic Powers Act (IEEPA) of 1977 gives the President the authority to impose tariffs.
The administration had used IEEPA to levy “reciprocal tariffs” and “trafficking tariffs” on products from China, Canada, and Mexico, arguing that trade imbalances and border security issues constituted a national emergency. However, the Supreme Court ruled that:
Tariffs are Taxes: Chief Justice John Roberts, writing for the majority, emphasized that the power to tax—which includes tariffs—belongs exclusively to Congress under Article I of the Constitution.
“Regulate” is not “Tax”: The Court held that IEEPA’s authority to “regulate importation” does not mean the President can unilaterally set tax rates
The Major Questions Doctrine: The Court applied this principle, stating that if Congress intended to delegate such massive economic power to the Executive Branch, it would have said so clearly and explicitly.
“The Framers did not vest any part of the taxing power in the Executive Branch,” wrote Chief Justice Roberts.
What Happens to the Money? The Refund “Mess”
One of the most pressing questions for businesses is the status of the billions of dollars already collected. Since 2025, the government has gathered an estimated $133 billion to $200 billion in IEEPA-based tariffs.
Court of International Trade (CIT) Action: Following the Supreme Court ruling, the CIT has ordered U.S. Customs and Border Protection (CBP) to begin preparing for a massive refund process.
The “Mess” Factor: Justice Brett Kavanaugh noted in his dissent that issuing these refunds will be a “mess.” It remains unclear exactly how and when businesses will see that money returned, as the Supreme Court did not provide a specific roadmap for the refund process
The Administration’s Pivot: Section 122 and 301
If you thought this ruling meant the end of tariffs, think again. Within hours of the decision, the administration began moving to alternative legal authorities:
Section 122 (Trade Act of 1974): The President implemented a temporary 10% global baseline tariff under this law. However, this power is limited to 150 days and a maximum rate of 15% unless Congress intervenes.
Section 301 Investigations: The U.S. Trade Representative (USTR) has launched new investigations into “structural excess capacity” and “forced labor” in countries like China and Mexico. These could lead to new, more legally “durable” tariffs in the coming months.
Section 232 Still Stands: Tariffs on steel and aluminum, which rely on a different national security statute, were not affected by this specific ruling and remain in place.
What This Means for You
For Businesses and Importers
The immediate relief from IEEPA tariffs is a win, but it is replaced by a new 10% surcharge under Section 122. You should:
Audit your entries: Identify which tariffs you paid were based on IEEPA to prepare for potential refund claims.
Stay Flexible: The trade environment remains volatile as the administration shifts its legal strategy to avoid future Court losses.
For Consumers
While the invalidation of billions in tariffs sounds like a price drop is coming, the introduction of the new 10% global tariff may offset those savings. Economists expect “trade-weighted” average tariff rates to remain higher than historical norms through 2026.
Summary of Key Impacts
Feature
IEEPA Tariffs (Struck Down)
Section 122 Tariffs (New)
Legal Status
Unconstitutional/Invalid
Currently Active
Current Rate
0% (Effective Feb 20, 2026)
10% (Effective Feb 24, 2026)
Duration
N/A
150 Days (Expires July 24, 2026)
Refunds
Likely, but process is TBD
No
The Supreme Court has drawn a firm line in the sand regarding the separation of powers. While the President still has significant tools to influence trade, the era of “unbounded” emergency tariffs appears to be over.
Starting or growing a business requires capital. While major banks are a common first thought, savvy entrepreneurs are increasingly looking toward credit unions. These member-owned cooperatives often provide a level of service and a focus on local community that large financial institutions can’t match. This guide will help you understand why a credit union might be the perfect partner for your small business loan and highlight some excellent examples.
Why Choose a Credit Union for Your Business Loan?
Unlike banks, which prioritize profit for shareholders, credit unions operate on a not-for-profit basis, existing solely to serve their members. This fundamental difference translates to several key advantages for business borrowers:
Competitive Rates and Fees: Credit unions often return their earnings to members through lower interest rates on loans and reduced fees. In a landscape where every dollar counts, these savings can be significant.
Personalized Service and Relationships: Loan officers at credit unions frequently live and work in the same community as you. They are more likely to take the time to understand your unique business plan, local market, and individual challenges, leading to a more collaborative and supportive lending process.
A Focus on the Local Economy: Credit unions thrive when their local communities thrive. By lending to small businesses, they are directly investing in local jobs, services, and growth. Your success is inherently linked to their mission.
A “Member-First” Mentality: You aren’t just a customer to a credit union; you are a member and a part-owner. This philosophy often results in a more empathetic and constructive approach, especially during tougher economic times. They may be more willing to work through setbacks and offer flexibility that larger banks wouldn’t consider.
Streamlined Decision-Making: Local credit unions often have a flatter organizational structure, meaning loan decisions can be made faster and by people who are directly accessible, rather than a centralized, distant corporate office.
Leading Examples (for inspiration, remember to research current 2026 options)
While specific rates and programs change rapidly, several credit unions consistently stand out for their robust and competitive small business lending offerings. As you conduct your research in March 2026, keep these institutions and their types in mind as a benchmark.
Navy Federal Credit Union: As the world’s largest credit union, Navy Federal (serving military members and their families) offers an extensive suite of business loans. They are well-known for their highly competitive interest rates, a diverse range of loan types (including SBA loans, term loans, and lines of credit), and a focus on assisting veterans and military families in their entrepreneurial journeys. If you meet the eligibility requirements, they are always a top contender to research.
America First Credit Union: Highly regarded in the Western United States, America First is a strong example of a regional powerhouse that delivers big-bank capabilities with credit union service. They offer a comprehensive range of commercial loans, including flexible terms, competitive rates, and specific expertise in industries common to their region. They often get high marks for technology integration and ease of doing business.
Digital Federal Credit Union (DCU): Though headquartered in the Northeast, DCU is another example of a credit union that serves members nationwide through its robust digital platform and community partnerships. They are often recognized for their competitive rates on both personal and business loan products and their simplified, tech-forward application processes, making them a good option for businesses looking for efficiency.
Local “Community-Hero” Credit Unions: This is often the best-kept secret. The strongest option for your business might be a credit union focused directly on your specific region or industry. These institutions possess unmatched understanding of your local market dynamics and may offer specialized loan programs designed to support niche local needs.
How to Find the Best Credit Union in March 2026
To find the ideal lending partner for your business right now, you need to conduct specific, up-to-the-minute research. The landscape shifts, and the “best” choice is always subjective to your unique needs. Follow these steps:
1. Gather Your Business Financials: The first step for any loan application is a solid business plan, detailed financial statements (P&L, balance sheet), and cash flow projections. This preparation shows you are serious and ready.
2. Define Your Loan Needs Precisely: How much capital do you need? What will the funds be used for (e.g., equipment, real estate, working capital)? Do you need a term loan or a flexible line of credit? Knowing this helps you narrow down which credit unions offer the most relevant programs.
3. Search for Eligibility First: Not everyone can join any credit union. Look for credit unions where you, your employees, or your business location make you eligible for membership. Some credit unions have broad eligibility (e.g., specific professions, community associations), making it easier than you might think.
4. Compare Rates, Terms, and Fees: Request specific quotes from at least 3-4 credit unions (and possibly one community bank for a point of comparison). Look beyond just the headline interest rate—examine the total cost of borrowing, including application fees, closing costs, and repayment terms.
5. Read Reviews and Testimonials: Talk to other local small business owners. Read online reviews. The experiences of your peers can provide invaluable insight into the speed of the loan process, the professionalism of the staff, and how supportive the institution is.
6. Schedule In-Person Meetings: If possible, meet with commercial loan officers from your top contenders. This allows you to ask detailed questions, present your business plan directly, and gauge whether they are truly interested in and enthusiastic about supporting your vision.
Choosing the right credit union for your business loan can make all the difference, not just in securing capital but in finding a long-term financial partner that understands your goals. By doing your homework and focusing on institutions that prioritize personalized service and community impact, you set your small business on the path to successful growth in March 2026 and beyond.
The final numbers for 2025 are in, and there has been a GDP Downward Revision… they’ve arrived with a bit of a chill. On March 13, 2026, the Bureau of Economic Analysis (BEA) released its second estimate for the fourth quarter of 2025, significantly revising real GDP growth downward to an annualized rate of 0.7%.
This is a sharp departure from the initial “advance” estimate of 1.4% and a massive deceleration from the robust 4.4% growth seen in the third quarter. For the full year, the U.S. economy grew by 2.1%, a slight dip from previous projections.
So, what happened at the end of the year to take the wind out of the economy’s sails?
The Culprits: Shutdowns, Slumps, and Spending
Several factors converged in late 2025 to create this “soft landing” that felt a little more like a bump.
The 43-Day Government Shutdown: The most visible drag was the historic federal government shutdown that spanned October and November. While essential services remained, the lack of federal paychecks and halted government contracts took a measurable bite out of domestic demand.
A “Low-Hire” Labor Market: While mass layoffs weren’t the headline, a “low-hire, low-fire” environment took hold. Monthly job gains slowed to a crawl, and the unemployment rate ticked up to 4.6% by November, making consumers more cautious with their wallets.
The Trade Drag: Exports were revised downward as global demand softened, and a “front-loading” effect—where companies rushed to import goods earlier in the year to avoid new tariffs—faded out, leaving a gap in activity for the final months.
Sticky Inflation: Despite the slower growth, the PCE price index (the Fed’s favorite inflation gauge) remained at 2.9%. This combination of stagnant growth and persistent inflation has put the Federal Reserve in a difficult “wait-and-see” position.
Silver Linings in the Data
It’s not all doom and gloom. Even with the downward revision, there are signs of underlying resilience:
Investment is Picking Up: While consumer spending moderated, business investment—particularly in AI infrastructure—actually accelerated in Q4, acting as a critical floor for the economy.
Market Resilience: Interestingly, Wall Street took the news in stride. Markets actually rallied following the release, as investors bet that the soft GDP data would finally force the Federal Reserve to consider more aggressive rate cuts later in 2026.
Recouping the Loss: Economists expect much of the “lost” output from the government shutdown to be recovered in the first half of 2026 as backlogged projects and federal spending finally hit the books.
What’s Next for 2026?
The downward revision confirms that the “Goldilocks” era of high growth and falling inflation has hit a snag. Most forecasters, including the IMF and S&P Global, now project a steady but modest growth rate of around 1.8% to 2.0% for 2026.
The big question remains the Federal Reserve. With growth at 0.7% but inflation still above their 2% target, the path to interest rate cuts remains narrow. For now, the “wait-and-see” approach is the only game in town.
1. The Tech Sector: From Growth to Efficiency
While the broader economy slowed, Tech remained a relative fortress, but the “flavor” of investment is changing.
AI Infrastructure as a Life Raft: Business investment in “Intellectual Property Products” (tech speak for software and AI R&D) was one of the few areas that actually accelerated in Q4 2025. Companies are doubling down on AI to find the efficiencies they need to survive a low-growth environment.
The “Low-Hire” Reality: Expect the “low-hire” trend to persist in Silicon Valley. With GDP growth revised downward, tech giants are focusing on “AI-driven productivity” rather than aggressive headcount expansion.
Valuation Pressure: While the stock market has been resilient, persistent 2.9% inflation means the Federal Reserve isn’t in a rush to slash rates. High-growth tech stocks are sensitive to interest rates; if those rates stay “higher for longer,” we may see more volatility in tech valuations throughout 2026.
2. The Real Estate Market: A Tale of Two Interests
The GDP Downward Revision has created a paradoxical situation for housing.
Mortgage Rate Relief? Traditionally, weak GDP data pushes bond yields down, which can lower mortgage rates. Many analysts now expect the 30-year fixed rate to drift toward 6.0%–6.2% in 2026. This could finally “unlock” homeowners who have been trapped by high rates.
The “Sentiment” Gap: The revision highlights a cooling labor market (unemployment at 4.6%). Even if mortgage rates drop, buyer “jitters” may keep the market from exploding. J.P. Morgan research suggests national home prices may stall at 0% growth in 2026 as demand and supply reach a fragile equilibrium.
Commercial Real Estate (CRE) Stress: The 0.7% GDP print is toughest on office and retail CRE. Slower economic activity means less demand for physical space, likely leading to more “strategic defaults” or building repurposing projects in 2026.
The Federal Reserve’s “Tightrope”
The GDP Downward Revision puts the Fed in a bind. Usually, 0.7% growth would trigger an immediate rate cut to “save” the economy. However, with inflation still at 2.9%, they risk reigniting price hikes if they move too fast.
The Bottom Line: 2026 will be the year of the “Efficiency Play.” Whether you are a tech firm or a homebuyer, the goal is no longer “growth at any cost,” but rather finding value in a slower, more deliberate economic landscape.
Headline: 📉 GDP Revised to 0.7%: What it means for Tech & Real Estate in 2026.
The “Second Estimate” for Q4 2025 is out, and the numbers confirm a significant cooling of the U.S. economy. Real GDP growth was revised down to an annualized 0.7%—a sharp drop from the earlier 1.4% estimate.
While the 43-day government shutdown in late 2025 played a major role, the ripple effects for 2026 are already taking shape:
💻 TECH: The era of “growth at any cost” is officially over. We’re seeing a pivot toward Efficiency Tech. While broader spending is cooling, investment in AI infrastructure is accelerating as companies scramble to automate their way out of a low-growth environment.
🏠 REAL ESTATE: It’s a paradox. Slower growth usually means lower mortgage rates, and we’re already seeing 30-year fixed rates dip toward 6.0%. However, with unemployment ticking up to 4.6%, buyer “jitters” are real. J.P. Morgan predicts a 0% national price growth for 2026—a true flatline.
⚖️ THE FED: Chair Jerome Powell and the FOMC are walking a tightrope. With inflation still “sticky” at 2.4%–2.9%, they can’t rush to cut rates despite the sub-1% growth.
The Bottom Line: 2026 will reward the “Lean and Leaner.” Whether you’re managing a portfolio or a product roadmap, efficiency is the new growth.
1/ 🚨 BREAKING: U.S. Q4 2025 GDP revised DOWN to 0.7% (from 1.4%). The 2025 “Cold Snap” is official. Here’s the 30-second breakdown of what this means for your wallet in 2026. 🧵👇
2/ Why the drop? The 43-day government shutdown was a massive anchor, but we also saw a deceleration in consumer spending and exports. The economy didn’t crash, but it definitely pulled the emergency brake. 🛑
3/ 💻 TECH IMPACT: Silicon Valley is staying “Low-Hire.” With 0.7% growth, companies are prioritizing AI-driven productivity over expansion. If it doesn’t automate a process or save a dollar, it’s not getting funded this year.
4/ 🏠 HOUSING IMPACT: Good news? Mortgage rates are sliding toward 5.8%–6.0%. Bad news? A weaker labor market means fewer people are ready to jump. Expect a “sideways” year for home prices. 📉➡️
5/ 🏦 FED WATCH: All eyes on the March 18 FOMC meeting. The market was hoping for cuts, but with inflation at 2.4%, the Fed might stay “Higher for Longer” to ensure the fire is out.
6/Summary: 2026 is the year of the “Efficiency Play.” Growth is slow, money is still relatively expensive, and AI is the only engine still revving. Stay nimble. #GDP #Economy #Inflation
📸 Instagram/Threads: The Visual Summary
Caption:
The numbers are in: The U.S. economy hit a “speed bump” at the end of 2025. 📉 GDP growth was just revised down to 0.7%.
What this means for you: ✅ Mortgage Rates: Might actually get a bit friendlier (seeing 5.8% – 6% averages). ✅ Tech: More AI tools, fewer new job postings. Efficiency is 👑. ✅ Inflation: Still hanging around 2.4%, keeping the Fed on high alert.
It’s not a recession—it’s a recalibration. 2026 is about playing the long game. ♟️