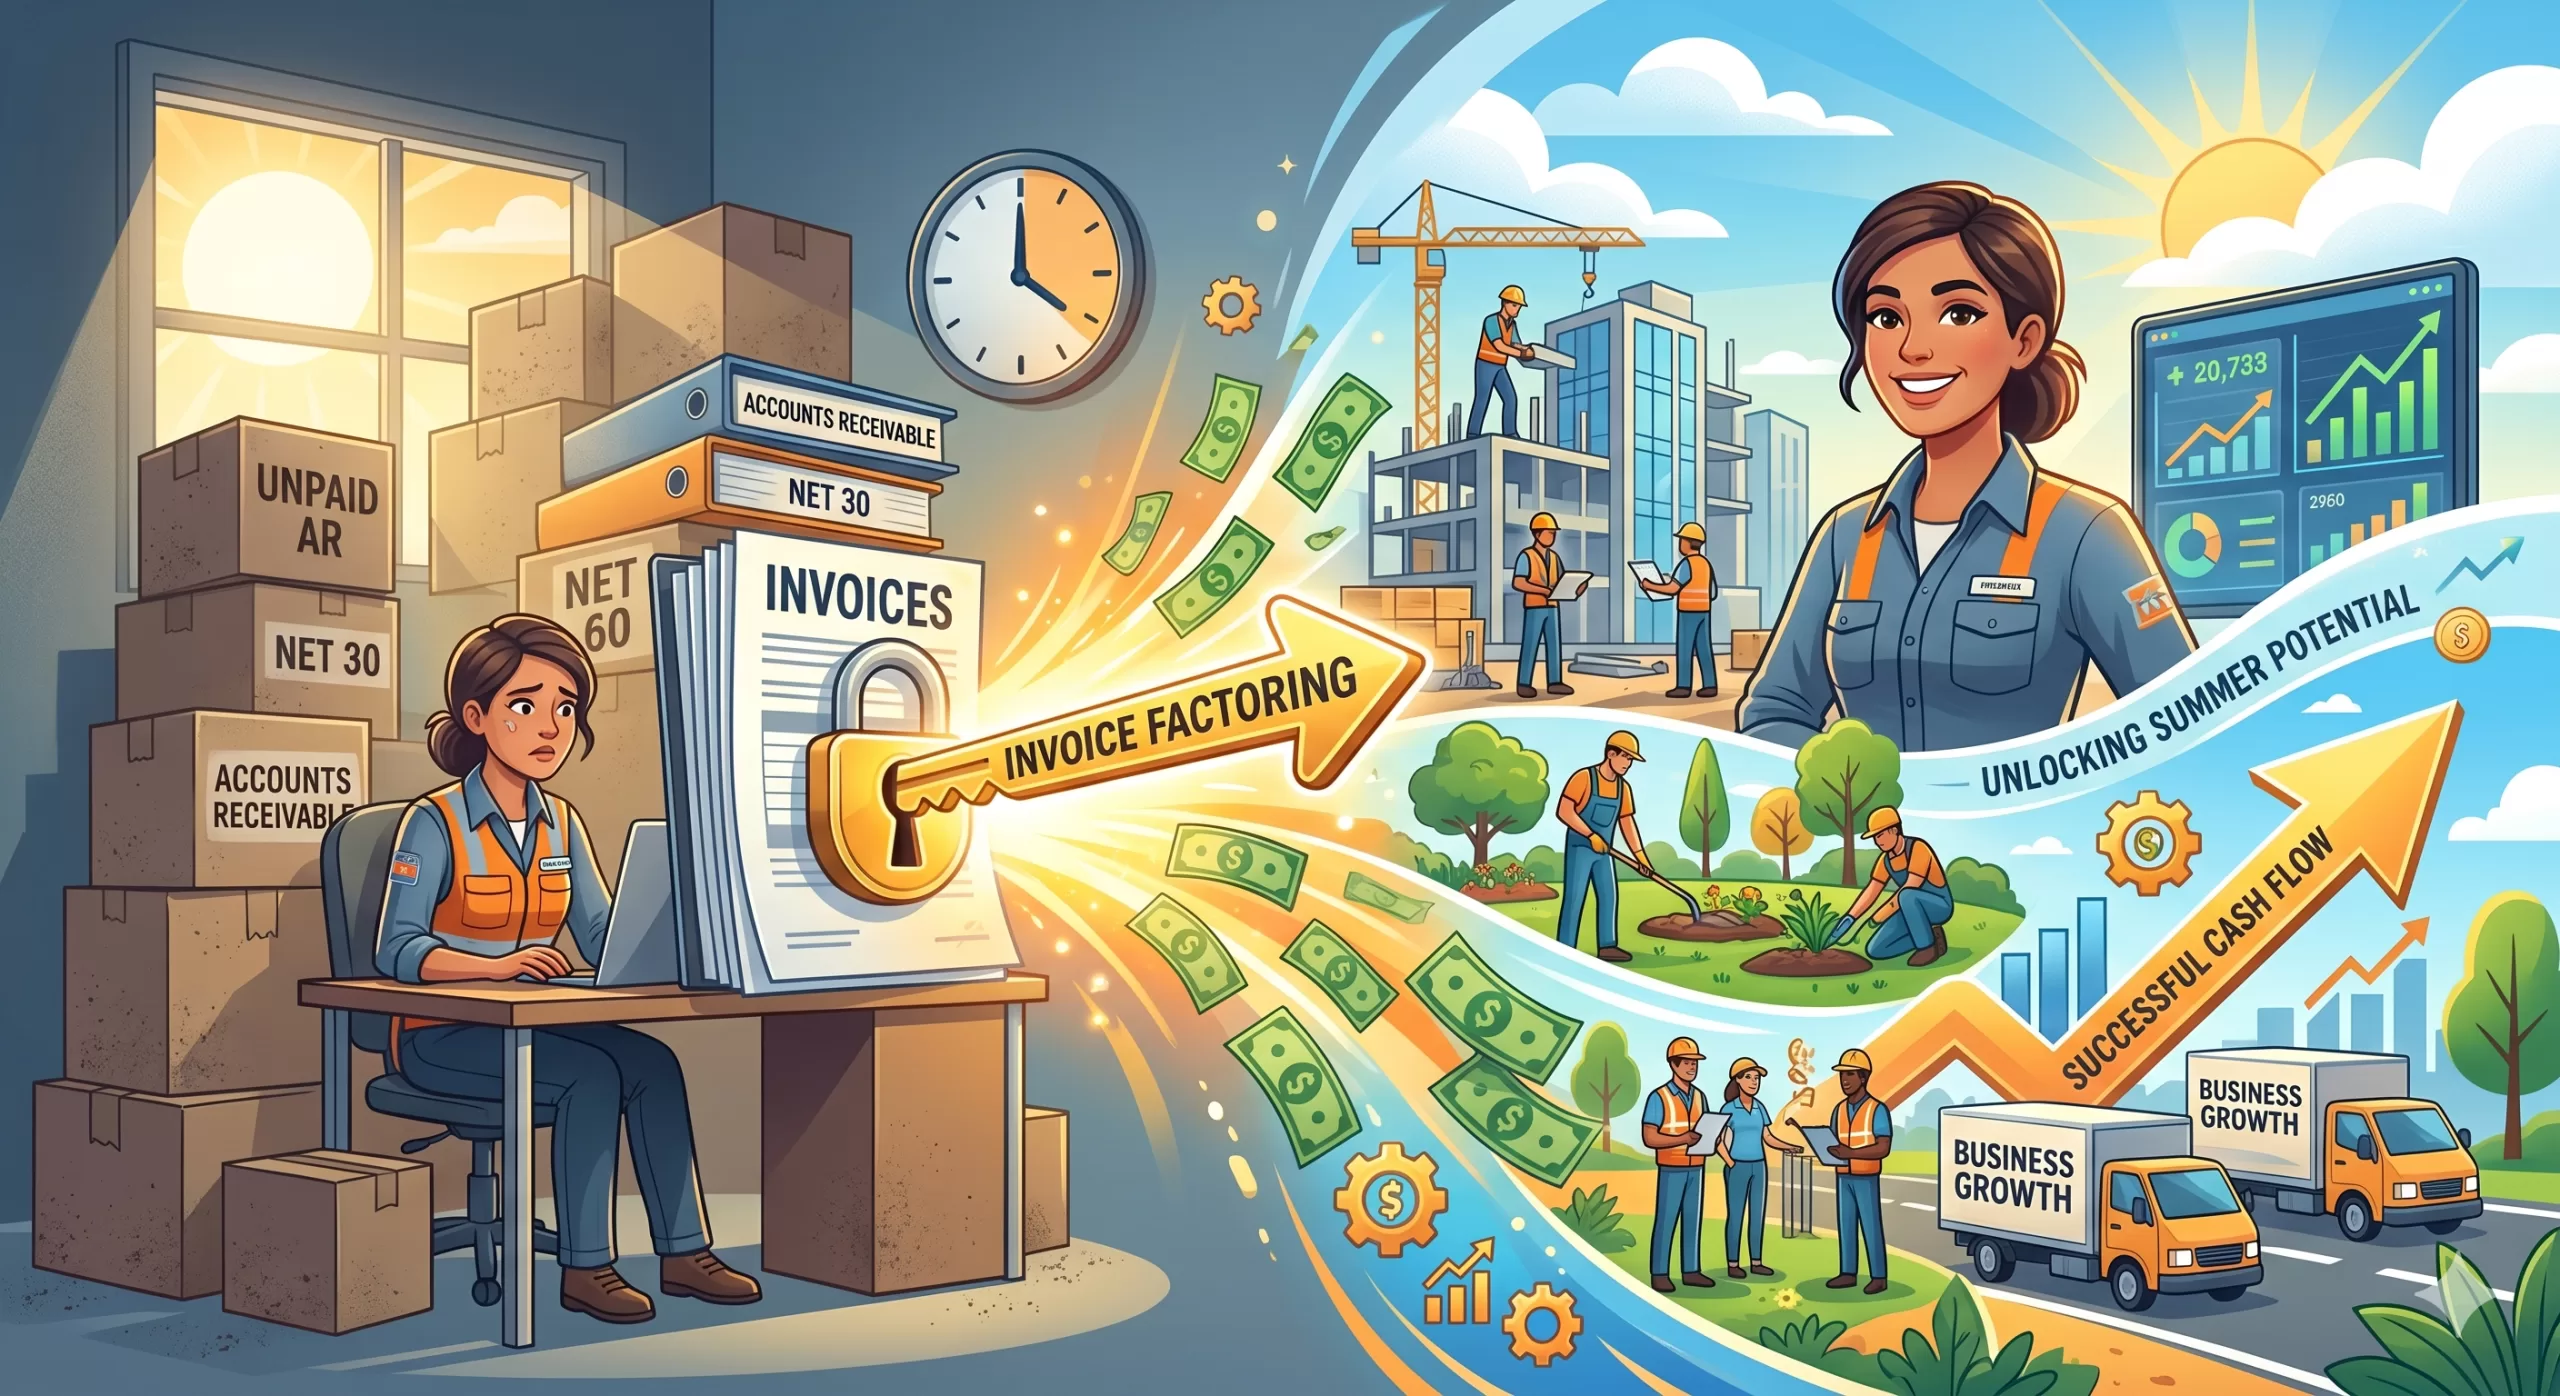
Summer acts as a brutal stress test for business cash flow. For seasonal industries, it’s a chaotic sprint that requires immediate cash to hire seasonal staff and buy inventory. For B2B service companies, summer often brings the dreaded “vacation slump”—decision-makers are out of the office, and Net-30 invoices suddenly stretch to Net-60 or Net-90. Consider Factoring.
In both scenarios, having your capital trapped in unpaid Accounts Receivable (AR) is a massive liability. If you have $100,000 sitting in your AR aging report but can’t make a $10,000 payroll on Friday, your business is technically growing but functionally starving.
This is where invoice factoringbecomes a critical tool to unlock your cash flow and keep your summer operations running smoothly.
What is AR Factoring?
Invoice factoring is not a loan; it is the sale of an asset. You are selling your outstanding B2B invoices to a third-party company (the factor) at a discount in exchange for immediate cash.
Here is how the standard mechanism works:
The Advance: You sell a verified invoice to the factor. They advance you the bulk of the invoice value immediately—typically 75% to 85%—usually within 24 to 48 hours.
The Collection: Your customer pays the factor directly according to your standard terms (e.g., 30 or 60 days).
The Rebate: Once the customer pays the invoice in full, the factor releases the remaining 15% to 25% to you, minus their factoring fee (which generally ranges from 1.5% to 2.5% per month of the invoice value, depending on how long it takes the customer to pay and their creditworthiness).
How Factoring Solves Summer Cash Flow Bottlenecks
Relying on AR factoring shifts your business from a defensive posture (waiting for checks to arrive) to an offensive one.
1. Funding the Summer Spike
If your business peaks between Memorial Day and Labor Day, you have to spend money before you make it. You need to repair equipment, purchase bulk materials, and onboard temporary employees. Factoring allows you to leverage the work you completed in May to fund the massive projects you are taking on in June, without waiting for the bank to approve a traditional line of credit.
2. Surviving the B2B Payment Slowdown
When your clients’ accounts payable departments go on summer vacation, your invoices sit on desks. Factoring insulates your business from your clients’ slow payment habits. By advancing the cash, the factor absorbs the wait time. You get the working capital you need to cover fixed overhead costs—like rent, software subscriptions, and core payroll—regardless of whether your client takes 30 or 75 days to pay.
3. Taking Advantage of Supplier Discounts
Suppliers often offer early-pay discounts (e.g., a “2/10 Net 30” deal, meaning a 2% discount if paid within 10 days). If your cash is tied up in AR, you miss these savings. Factoring gives you the liquidity to pay your suppliers upfront. Often, the supplier discount you secure by having cash on hand will offset a significant portion of the factoring fee.
Strategic Considerations Before You Factor
While factoring is highly accessible—because factors care more about your customers’ credit scores than your own—it requires strategic management:
Mind your profit margins: Factoring makes the most sense for businesses with healthy margins (typically 15% or higher). If you operate on razor-thin margins, giving up 2% to 4% of your gross revenue to a factor can wipe out your profitability.
Recourse vs. Non-Recourse: Understand the terms you are signing. In recourse factoring (the most common and affordable type), if your customer ultimately defaults and never pays the invoice, you must buy the invoice back from the factor. In non-recourse factoring, the factor absorbs the loss if the customer goes bankrupt, but you will pay higher fees for that protection.
If unpaid invoices are the only thing standing between you and a highly profitable summer season, AR factoring is one of the fastest ways to turn your ledger into liquid capital. By treating your receivables as immediate cash, you can stop acting as a free bank for your clients and start investing in your own growth.
Press Release: (March 26, 2026) Versant Funding LLC is pleased to announce that it has funded a $1.4 Million non-recourse factoring facility to a manufacturer of equipment used by global auto companies.
While our newest client has successfully secured contracts with some of the world’s largest manufacturers, slow-paying accounts receivable are putting pressure on the company’s cash flow and preventing them from taking on new business.
“In evaluating a funding opportunity, Versant focuses exclusively on the quality of our client’s accounts receivable” according to Chris Lehnes, Business Development Officer for Versant Funding, and originator of this transaction. “Since this company’s customers are among the strongest on the planet, our facility will essentially have no cap and will grow automatically as the company’s AR balances increase, providing our client the cash needed to expand.”
About Versant Funding: Versant Funding’s custom Non-Recourse Factoring Facilities have been designed to fill a void in the market by focusing exclusively on the credit quality of a company’s accounts receivable. Versant Funding offers non-recourse factoring solutions to companies with B2B or B2G sales from $100,000 to $30 Million per month. All we care about is the credit quality of the A/R. To learn more contact: Chris Lehnes|203-664-1535 | chris@chrislehnes.com
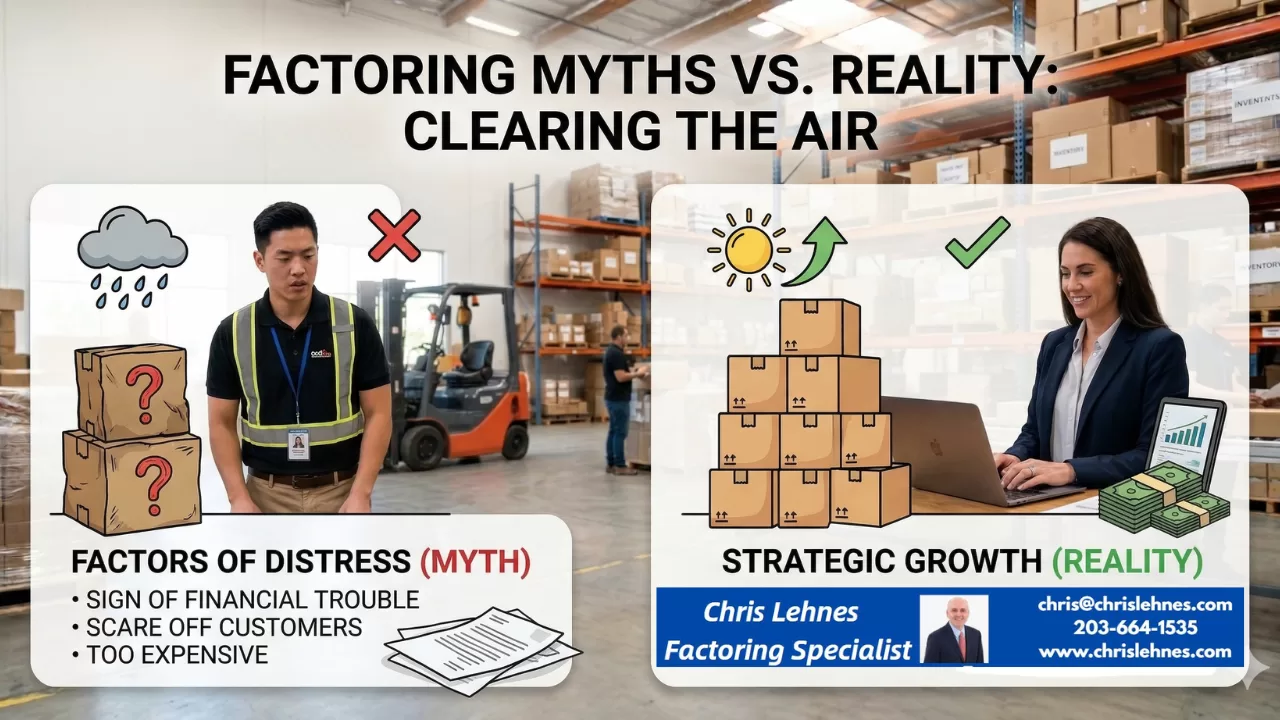
For many distributors, the word “factoring” carries some outdated baggage. If you’re hesitant to pull the trigger, it’s likely because of one of these common misconceptions. Let’s separate the noise from the facts:
The Myth
The Reality
“Factoring is a sign of financial trouble.”
Factoring is a sign of growth. Most companies use factoring because they are growing too fast for their cash flow to keep up. It’s a strategic choice to fuel expansion, not a last-ditch effort to stay afloat.
“My customers will think I’m going under.”
It’s a standard B2B practice. Major retailers and manufacturers deal with factors every day. In many industries, like apparel or electronics distribution, it’s actually the “gold standard” for managing receivables.
“It’s way too expensive.”
Look at the ROI. While the fee (1–3%) is higher than a bank loan, the “cost of waiting” 60 days for a check often means missing out on new inventory or early-pay discounts from your own suppliers that could actually save you more than the factoring fee.
“I’ll lose control of my customer relationships.”
You stay in the driver’s seat. Modern factoring companies act as a professional extension of your back office. They want your customers to stay happy so they keep buying (and paying). You still manage the sales and service; they just handle the math.
“It’s just like a high-interest loan.”
It’s not a loan at all. Because you are selling an asset (your invoice), you aren’t taking on debt. There are no monthly principal or interest payments to worry about—the “payment” comes from your customer, not your bank account.
The “Silent” Benefit: Professional Credit Checks
One “Reality” that distributors often overlook is that a factor acts as a free credit department. Before you ship $50,000 worth of goods to a new client, you can ask your factor to check their credit. If the factor won’t buy the invoice, that’s a massive red flag that you probably shouldn’t be selling to that customer on terms in the first place.
What is Factoring: In the world of distribution, the “growth paradox” is a real headache. You land a massive new retail contract—which is great news—but suddenly you’re shelling out for inventory and shipping costs while your customer sits on a 60- or 90-day payment term.
For many distributors, waiting for those invoices to clear creates a suffocating bottleneck. This is where Accounts Receivable (AR) Factoring comes in. It’s not a loan; it’s a financial tool that turns your unpaid invoices into immediate working capital.
How It Works: The Quick Breakdown
Instead of waiting months for a customer to pay, you sell your outstanding invoices to a “factor” (a specialized financial company).
The Advance: The factor typically advances you 80% to 90% of the invoice value within 24 hours.
The Collection: The factor handles the collection from your customer.
The Rebate: Once the customer pays, the factor sends you the remaining balance, minus a small fee (usually 1–3%).
4 Major Benefits for Distributors
1. Bridge the Inventory Gap
Distributors often have to pay suppliers long before they get paid by their own clients. Factoring provides the liquidity to pay your manufacturers upfront, often allowing you to take advantage of early-payment discounts that can actually offset the cost of the factoring fee itself.
2. Fuel Rapid Scalability
Traditional bank loans are limited by your credit history or collateral. Factoring, however, scales with your sales. The more you sell to reputable customers, the more funding becomes available. It allows you to say “yes” to large orders that you otherwise couldn’t afford to fulfill.
3. Professional Credit Management
Many factoring companies act as an extension of your back office. They perform credit checks on your potential customers, helping you avoid “bad seeds” before you ship a single pallet. This reduces your risk of bad debt and saves your team the awkwardness of making collection calls.
4. No New Debt
Since factoring is the purchase of an asset (your invoice) rather than a loan, it doesn’t show up as debt on your balance sheet. This keeps your debt-to-equity ratio clean, making your business look much healthier to future investors or traditional lenders.
Is It Right For You?
Factoring is particularly powerful if you are:
A startup with a thin credit history but blue-chip customers.
Experiencing seasonal spikes that drain your cash reserves.
Tired of the “waiting game” associated with 30, 60, or 90-day terms.
While there is a cost involved, the ability to reinvest that cash immediately into new inventory or operations often outweighs the fee. In the fast-moving world of distribution, speed is a competitive advantage.
Factoring vs. A Traditional Line of Credit: A Distributor’s Comparison
While both tools solve cash flow problems, they operate very differently. Here is how they stack up for a growing distributor:
Feature
AR Factoring
Traditional Bank Line of Credit (LOC)
Funding Limit Based On…
The creditworthiness of your customers and your accounts receivable balance.
Your business’s credit history, profitability, and your collateral.
Speed of Funding
Extremely fast. Setup takes a few days; once active, funding often occurs within 24–48 hours of invoice verification.
Slow. The approval process can take weeks or even months.
Debt Type
Not Debt. It is the “asset purchase” of your invoices.
Debt. This is a loan that appears as a liability on your balance sheet.
Impact on Credit
Boosts Credit Score. It provides cash to pay your suppliers and operational debts on time.
Lowers “Available” Credit. Utilizing the full LOC can temporarily lower your score until it’s paid down.
Administrative Support
The factor often provides credit management and collection services, freeing up your back office.
You retain full responsibility for all collections and monitoring customer credit.
Scalability
Unlimited. As your credit-worthy sales grow, your available funding automatically increases.
Capped. Your limit is fixed and requires a re-application process to increase.
Gemini said
Certainly. Here is a comparison table and a section you can drop directly into your blog post.
Factoring vs. A Traditional Line of Credit: A Distributor’s Comparison
While both tools solve cash flow problems, they operate very differently. Here is how they stack up for a growing distributor:
Feature
AR Factoring
Traditional Bank Line of Credit (LOC)
Funding Limit Based On…
The creditworthiness of your customers and your accounts receivable balance.
Your business’s credit history, profitability, and your collateral.
Speed of Funding
Extremely fast. Setup takes a few days; once active, funding often occurs within 24–48 hours of invoice verification.
Slow. The approval process can take weeks or even months.
Debt Type
Not Debt. It is the “asset purchase” of your invoices.
Debt. This is a loan that appears as a liability on your balance sheet.
Impact on Credit
Boosts Credit Score. It provides cash to pay your suppliers and operational debts on time.
Lowers “Available” Credit. Utilizing the full LOC can temporarily lower your score until it’s paid down.
Administrative Support
The factor often provides credit management and collection services, freeing up your back office.
You retain full responsibility for all collections and monitoring customer credit.
Scalability
Unlimited. As your credit-worthy sales grow, your available funding automatically increases.
Capped. Your limit is fixed and requires a re-application process to increase.
Which One Wins for Distributors?
A bank line of credit is almost always the cheapest form of capital if you can get approved for a large enough limit.
However, for distributors in a hyper-growth phase, or those whose balance sheets don’t match their ambition, AR factoring offers unmatched speed and scalability. It allows you to leverage your customers’ financial strength to fund your own growth.
The Final Verdict: When to Choose Factoring
For a distributor, the choice between factoring and other financing boils down to your growth trajectory and customer base.
A traditional bank line of credit is often the lowest-cost option, but it is also the most rigid. If you have years of steady profitability and a “boring” (predictable) growth curve, the bank is your best friend.
However, AR factoring is the superior choice if:
You are growing faster than your cash flow allows: If a sudden 50% increase in orders would actually break your business because you can’t afford the inventory, you need factoring.
You have “lumpy” revenue: If you deal with seasonal spikes where you need $500k in October but only $50k in January, the flexibility of factoring is unmatched.
Your customers are larger than you: If you are a small distributor selling to giants like Walmart or Amazon, a factor will look at their multi-billion-dollar credit rating to fund you, rather than your own limited history.
Ultimately, factoring isn’t just a way to get paid early—it’s a way to weaponize your accounts receivable to outmaneuver competitors who are still stuck waiting for a check in the mail.
(March 19, 2026) Versant Funding LLC is pleased to announce that it has funded a $5 Million non-recourse factoring facility to a 90+ year-old company that provides services to major consumer brands.
After acquisition by a Private Equity Group, our latest client’s new management team implemented a turnaround plan which required additional cash. While the company was in the process of applying for an asset-based line of credit, time was of the essence and a funding date for the ABL facility was uncertain.
“Versant can fund faster than most traditional financing sources because we focus solely on the credit quality of our clients’ customers and do not perform a full underwriting or audit of the business” according to Chris Lehnes, Business Development Officer for Versant Funding, and originator of this financing opportunity. “Since this company’s customers include some of the world’s strongest consumer brands, we quickly approved the transaction and were ready to fund in about a week.”
Versant Funding’s custom Non-Recourse Factoring Facilities have been designed to fill a void in the market by focusing exclusively on the credit quality of a company’s accounts receivable. Versant Funding offers non-recourse factoring solutions to companies with B2B or B2G sales from $100,000 to $30 Million per month. All we care about is the credit quality of the A/R. To learn more contact: Chris Lehnes |203-664-1535 | chris@chrislehnes.com
The first few warm days of spring mean flowers, baseball, and for many small business owners in March 2026, the annual financial checkup. If you’ve looked at your numbers and realized you need a cash injection for new equipment, that third location, or an aggressive inventory build, you know the drill: It’s time to find the capital. While large national banks are the obvious choice, they are often difficult, impersonal, and slow. By comparison, credit unions have become the unexpected superstars of commercial lending, especially for small and medium-sized enterprises (SMEs).
If you are hunting for a business loan this month, you need to understand why credit unions are dominating and how to find the one that will actually make that critical “yes” happen for your business.
The Not-So-Secret Advantage of the Member-Owner
To understand why credit unions often beat banks on business lending, you have to look at their structure.
Banks answer to shareholders who demand profits and high returns on equity. Every decision, including who gets a loan, is filtered through the lens of maximizing shareholder value.
Credit unions, however, are not-for-profit cooperatives. They do not have public stock. Their members (you, me, and other account holders) are the owners.
This single difference ripples through every interaction. For business lending in 2026, it means:
1. Rates and Fees That Just Make More Sense: Instead of returning profit to Wall Street, credit unions reinvest earnings back into the institution and their members. This often manifests as lower interest rates on commercial loans and significantly lower loan-origination and maintenance fees. In 2026, when inflation has been a recent headache, a difference of 0.5% on a large loan term can mean thousands of dollars saved.
2. Hyper-Local Expertise: When you sit down with a commercial lender at a bank, their rules, algorithms, and models might be set at headquarters 2,000 miles away. They may not understand the specific micro-market in Newtown, Connecticut, where you are operating. But your local credit union officer lives here. They understand why opening a second pizza parlor on the new development is a smart bet, not a risky venture. They lend based on local market knowledge.
3. Relationships Over Risk-Scores: A bank will look at your credit score and financial statements, enter them into a model, and receive a automated “Approve” or “Deny.” Credit unions, especially smaller, focused ones, prioritize relationships. They are more likely to have a real human look at your complete business plan, understand your unique vision, and listen to the story behind your application, not just the numbers on the page.
The “New Reality” of SBA Lending
One of the most important developments in 2026 is that the Small Business Administration (SBA) has made it significantly easier and faster for credit unions to facilitate SBA 7(a) and 504 loans.
For many small businesses, these government-backed loans are the Holy Grail: long terms, lower interest rates, and lower down-payment requirements. Previously, massive banks dominated this space because the paperwork was crushing.
However, the “Streamline and Connect Act” of 2024 (as we projected) drastically simplified the SBA application process and created digital interfaces specifically designed for smaller community financial institutions.
This means that in March 2026, the local credit union you never expected to handle an SBA application is now a Preferred Lender, capable of getting your government-backed loan approved in weeks, not months.
How to Evaluate a Credit Union in March 2026
You can’t just walk into the nearest credit union and expect a perfect loan offer. To find the “best” one for your business right now, you must be strategic:
Step 1: Membership Criteria (The Gateway)
Credit unions can’t just lend to anyone. They operate under a specific “field of membership” (FOM). While some have broadened their charters, many are still strictly limited. To find the “best,” you must find the one you can actually join.
Geographic FOM: Are you eligible because your business is located in Newtown, CT, or the surrounding county? This is the most common path.
Associational or Professional FOM: Are you a veteran? An educator? A first responder? A member of a specific local church or union? There are niche credit unions specialized for these groups, and they often offer highly beneficial industry-specific lending programs.
Step 2: Technology and Speed
While personal relationships are the hallmark of credit unions, it’s 2026. You should not have to wait 30 days for a response to your application. A strong, business-friendly credit union will have a fast, streamlined digital application portal.
They should have digital tools that connect directly to your accounting software (like QuickBooks or Xero), allowing their lenders to instantly verify your cash flow without forcing you to hunt down piles of paper bank statements. If a credit union’s website looks like it hasn’t been updated since 2018, that is a massive red flag.
Step 3: Ask About Specific Business Expertise
The credit union that is excellent for a car loan or a personal mortgage is not necessarily the best choice for a $500,000 commercial line of credit to finance inventory for a manufacturing business.
When you interview a prospective credit union, ask about their experience in your industry. A credit union that specializes in healthcare practice lending will have different perspectives and better loan structures than one that primarily works with general contractors.
The March 2026 Takeaway: Don’t Lead with a Bank
Your default shouldn’t be the massive financial conglomerate that you can only reach via an 800-number. Your first stop in 2026 should be your local, community-focused credit union. They are built to serve owners like you, and they have the tools and local knowledge to help your business take flight this spring.
While the macro economy is feeling the “pump shock,” the impact on small business lending and accounts receivable (AR) factoring is more nuanced. For many industries, rising oil prices act as a catalyst for alternative financing, as traditional bank credit tends to tighten just when operational costs spike.
1. Impact on Small Business Lending
Traditional bank lending to small businesses is becoming more restrictive as energy-driven inflation persists.
The “Double Squeeze”: Small businesses are facing higher input costs (fuel/transport) alongside high interest rates. Banks, wary of compressed profit margins, are increasing their underwriting scrutiny.
The Approval Gap: As of early 2026, large banks are approving only about 68% of small business loans, compared to 82% at smaller, community-focused institutions.
Pivot to High-Cost Credit: With traditional loans taking weeks to approve, many businesses are turning to credit cards (averaging 18%–36% interest) to cover immediate fuel and supply chain gaps, significantly increasing their long-term debt burden.
2. The Surge in AR Factoring Demand
In a high-oil-price environment, factoring often shifts from a “last resort” to a strategic cash-flow tool, particularly for energy-intensive sectors.
Fuel as a Fixed, Immediate Expense: In industries like trucking and oilfield services, fuel must be paid for daily or weekly, while customers (shippers or large operators) often demand 30- to 90-day payment terms. Factoring bridges this “cash gap” without adding traditional debt to the balance sheet.
Sector-Specific Trends:
Transportation/Trucking: Factoring companies are seeing record demand. These businesses often enjoy the highest advance rates (90%–97%+) because their invoices are backed by tangible freight delivery.
Oilfield Services: As drilling activity ramps up in response to higher prices (especially in the Permian Basin), service providers are using factoring to scale quickly—buying new equipment or meeting surge payroll without waiting for 60-day payouts from major oil producers.
Manufacturing: With raw material costs rising alongside energy, manufacturers are factoring invoices to maintain liquidity reserves to buy inventory before prices hike further.
Factoring vs. Traditional Lending in 2026
Feature
Traditional Bank Loan
AR Factoring
Approval Basis
Business credit & history
Customer (Debtor) credit
Speed of Funding
2 – 7 weeks
24 – 48 hours
Debt Load
Increases liability on balance sheet
No new debt (selling an asset)
Scalability
Fixed limit
Grows with your sales volume
Cost
Lower interest (6%–12%)
Higher fees (1%–5% per 30 days)
Strategic Outlook
For the remainder of 2026, businesses that rely on “floating” cash flow are likely to prioritize speed over cost. While factoring fees are higher than bank interest, the ability to access cash within 24 hours to pay for $4.00/gallon diesel is often the difference between staying operational and grounding a fleet.
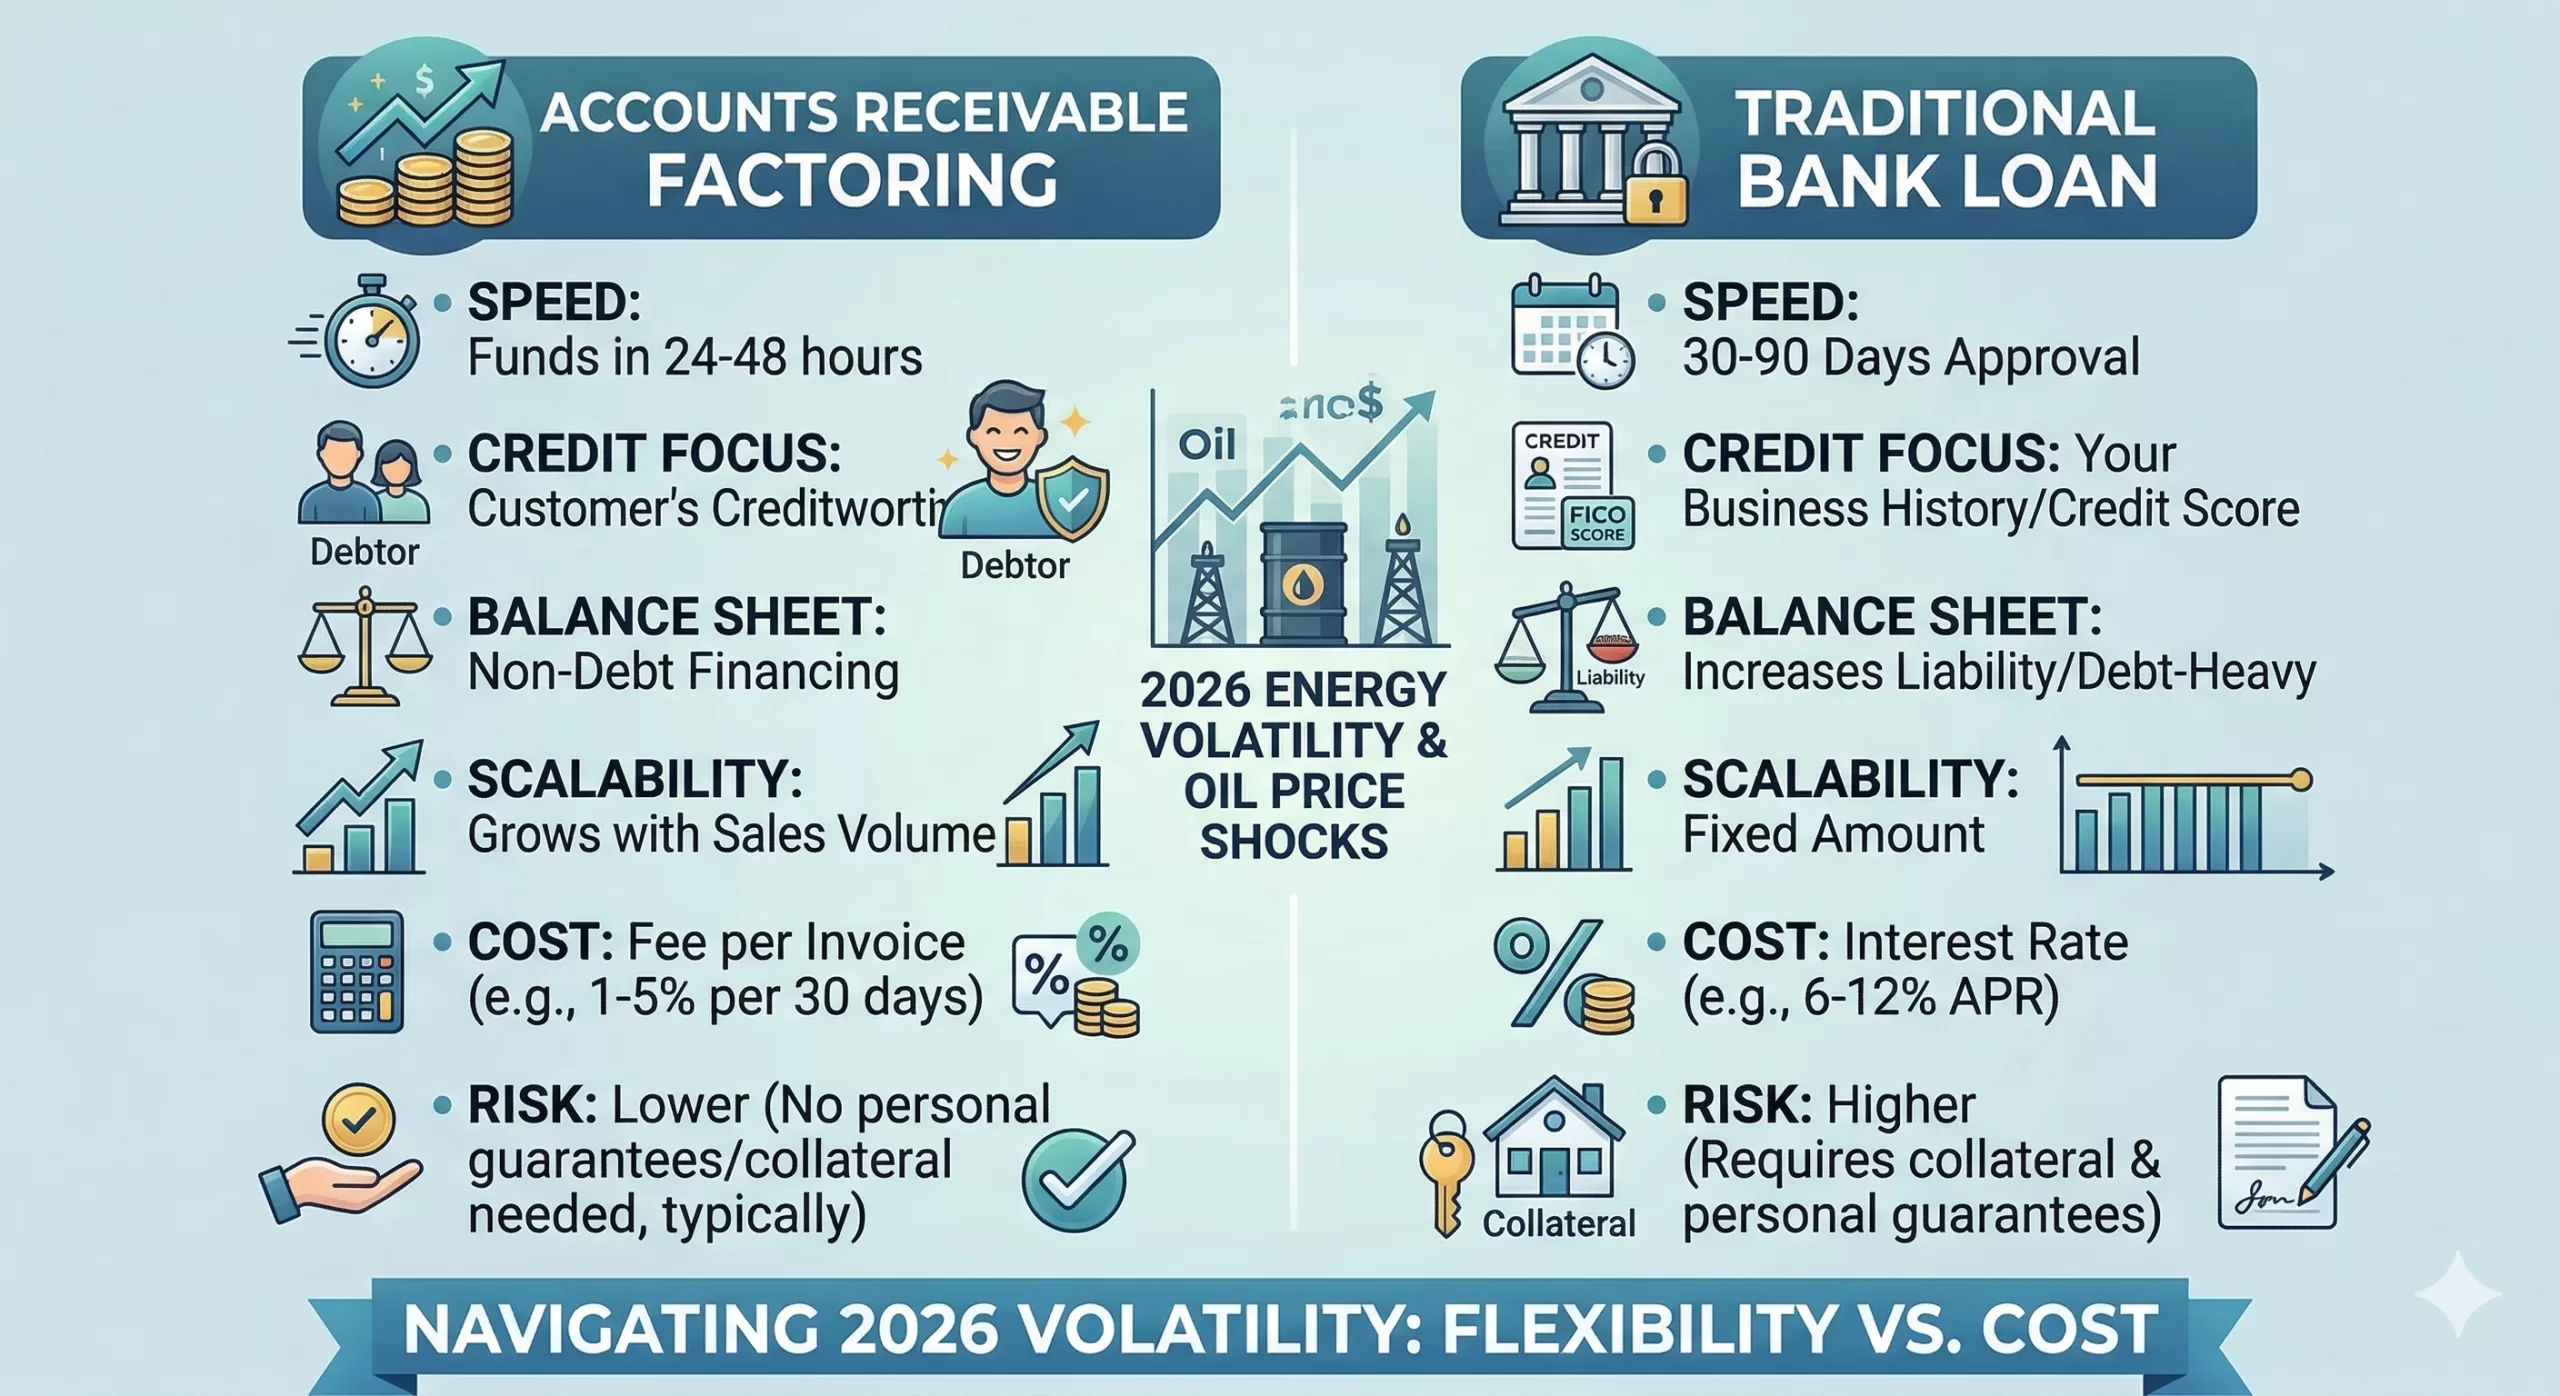
In a volatile economy where oil prices are surging and traditional banks are pulling back, choosing the right financing tool is a high-stakes decision. For B2B businesses—especially those in staffing, digital marketing, and manufacturing—the choice often comes down to the speed of Factoring versus the lower cost of a Bank Loan.
Below is a strategic comparison designed to help you evaluate which path aligns with your current cash flow needs.
Factoring vs. Bank Loans: 2026 Strategic Comparison
Feature
Accounts Receivable Factoring
Traditional Bank Loan
Speed to Cash
Ultra-Fast: Funds usually arrive within 24–48 hours after invoice setup.
Slow: Approval typically takes 30–90 days of underwriting.
Credit Focus
The Debtor: Decisions are based on your customer’s credit and payment history.
The Business: Based on your FICO score, tax returns, and years in business.
Balance Sheet
Debt-Free: It is the sale of an asset (invoices), not a liability.
Debt-Heavy: Adds a liability that can impact your debt-to-income ratio.
Scalability
Unlimited: As your sales grow, your available cash grows automatically.
Fixed: You are capped at a set amount and must re-apply to increase it.
Total Cost
Higher Fees: Usually 1%–5% per 30 days (effective APR is higher).
Lower Rates: Typically 6%–12% APR for qualified businesses.
Risk
Low: No collateral like your house or equipment is typically required.
High: Often requires a blanket lien on assets or personal guarantees.
Export to Sheets
The “Why Now?” Factor: Navigating 2026 Volatility
Pros of Factoring in This Market
Immediate Fuel/Supply Buffer: With diesel prices fluctuating, factoring gives you the cash today to buy inventory or fuel before the next price hike.
Protects Your Growth: In sectors like digital marketing or staffing, you can’t wait 60 days for a client to pay to meet your weekly payroll. Factoring ensures your team stays paid regardless of when the client cuts the check.
No “Covenant” Stress: Bank loans often come with strict “covenants” (rules about your profit margins). If high oil prices temporarily squeeze your margins, a bank might call your loan; a factor simply keeps funding your sales.
Cons to Consider
Margin Impact: If your profit margins are already thin (common in food production or distribution), the 1%–3% factoring fee could eat up a significant portion of your net income.
Customer Perception: While widely accepted today, some ultra-conservative clients might still prefer to pay you directly rather than a third-party factor.
The Bottom Line
If you have long-term stability and time to wait, a Bank Loan is cheaper. However, if you are growing rapidly or facing unpredictable costs, Factoring acts as a flexible insurance policy for your cash flow.